Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
November 14, 2025

Mining Production and Sales

September 2025
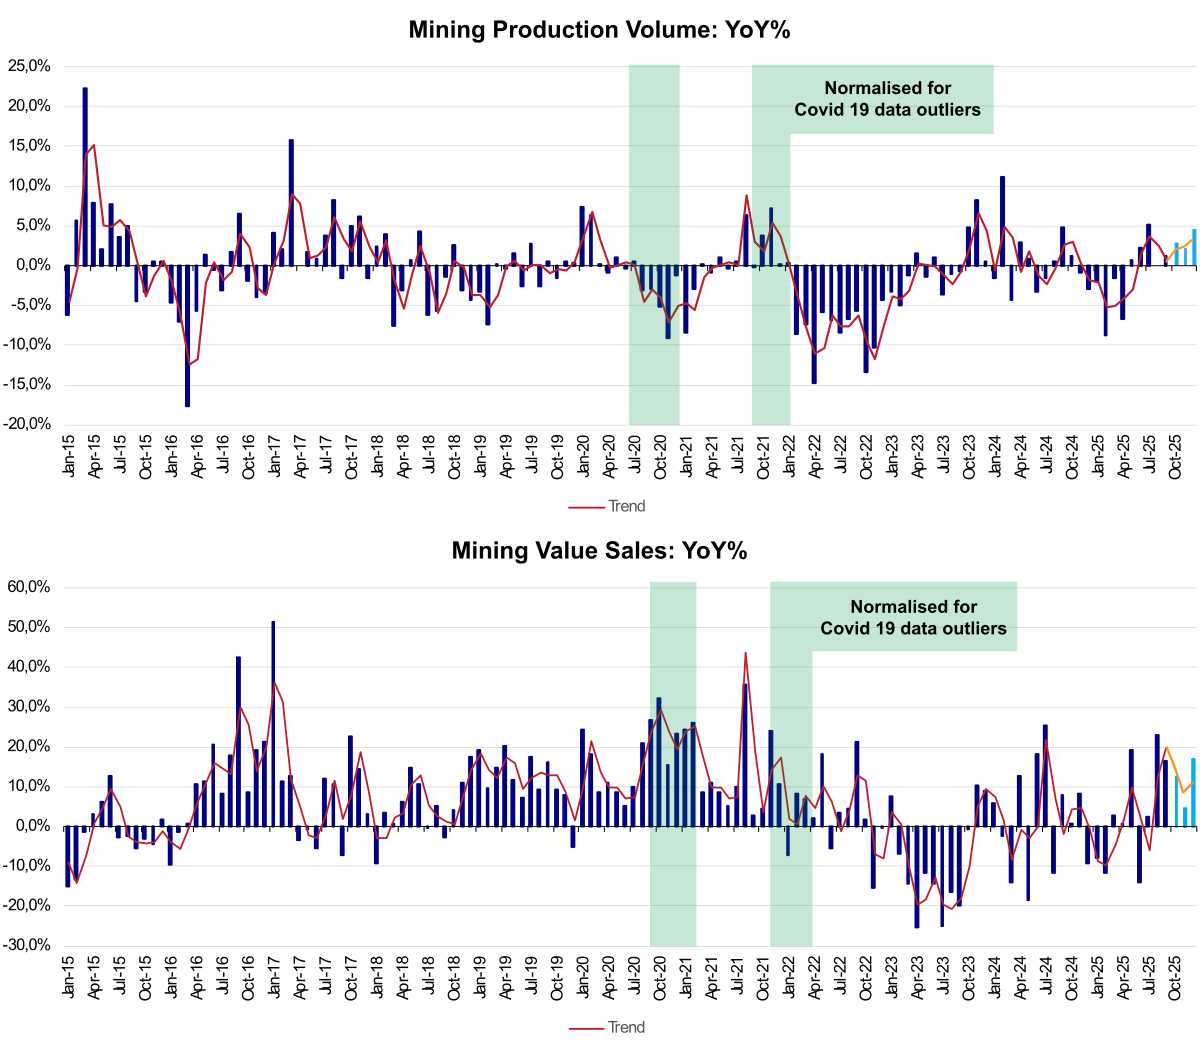
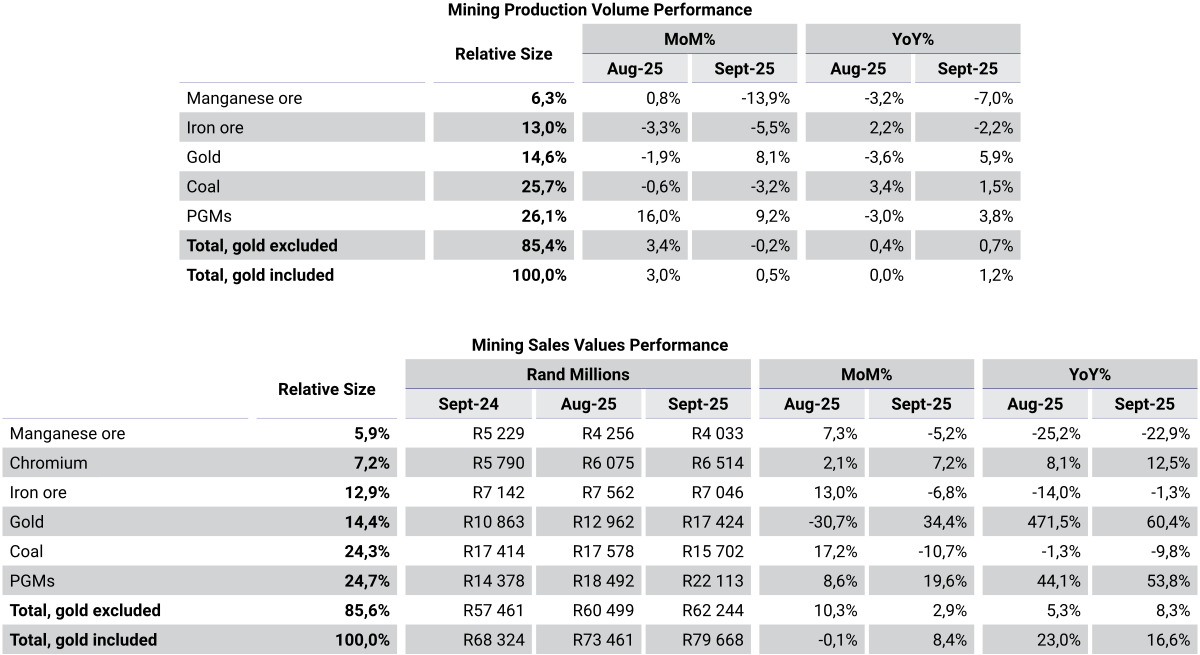
In September 2025, mining activity in South Africa increased by 1.2% year-on-year, after remaining unchanged in August.

This growth was primarily driven by:

  • A 6.7% increase in platinum production, which contributed 1.1 percentage points to the overall mining output for the month.
  • A 5.9% rise in gold production, adding a further 0.6 percentage points.
  • A 1.5% increase in coal mining, contributing an additional 0.4 percentage points to total monthly production.

For the third quarter of 2025, seasonally adjusted mining production rose by 2.5% compared to the previous quarter. The quarterly growth was mainly driven by:

  • Platinum mining, which expanded by 6.7%, contributing 1.7 percentage points.
  • Coal production, which increased by 1.0%, adding 0.3 percentage points.
  • Manganese ore, which grew by 6.8%, contributing a further 0.5 percentage points.

Nominal mining sales climbed by 16.6% in September. Several subsectors, notably supported this positive trend:

  • Platinum sales, which surged by 53.8%, contributing 11.3 percentage points to total mining sales growth.
  • Gold sales, which increased significantly by 60.4%, adding 9.6 percentage points.
  • Chromium ore sales, which rose by 12.5%, contributing another 1.1 percentage points.

However, some segments negatively impacted mining sales:

  • Coal sales, which declined by 9.8%, subtracting 2.5 percentage points.
  • Manganese ore sales, which fell by 22.9%, reducing sales by 1.8 percentage points.

The mining sector remains vital to South Africa’s economy, generating foreign exchange and providing employment for approximately 449,000 people, 16 000 more than in the previous quarter, according to StatsSA labour statistics for the third quarter of 2025. The sector grew by 3.7% from the first to the second quarter of 2025, based on recent GDP data. This quarterly growth is encouraging, given the sector’s ongoing importance for employment and foreign earnings.

Employment within the industry has slightly increased compared to the previous quarter, underscoring its continued significance. Nonetheless, several challenges persist, including concerns over exports to the US following new tariff measures introduced on 7 August, proposed export tariffs on manganese, and import tariffs on steel exports to the Eurozone. The sector also faces difficulties related to the loss of AGOA benefits in September and ongoing issues surrounding the new Mining Charter.

On the international front, geopolitical tensions between the US and China—characterised by trade conflicts and tariff disputes—continue to disrupt global markets and limit trade flows. However, some positive developments have emerged, such as the temporary exemption of certain mining materials used in steelmaking from high US tariffs. This provides some relief for the sector, which remains crucial to South Africa’s economy in terms of employment, foreign exchange, and overall growth.


More Coverage

South Africa recorded a trade surplus of R20.4 billion in August 2026, as exports continued to outpace imports. Export growth has exceeded import growth over the first eight months of the year, reflecting subdued domestic demand among businesses and consumers. But with higher fuel prices and tighter monetary policy expected to weigh on spending, demand is likely to recover only gradually. Read the full report for a closer look at the trade figures and what they could mean for South Africa’s economy in the months ahead.
South Africa’s credit market is showing surprising resilience, with credit demand rising by 7.5% in August 2026 despite renewed interest-rate pressure, elevated inflation and mounting household costs. While mortgage advances continued to grow, the fragile recovery in the property market highlights the strain caused by subdued investment, high debt levels and rising municipal and energy expenses. At the same time, sluggish instalment credit growth and continued reliance on short-term borrowing reveal how consumers are navigating increasingly difficult financial conditions. With higher oil prices, geopolitical risks and further SARB tightening adding to the pressure, this report examines what the latest credit trends reveal about household finances, business confidence and the broader South African economy.
South Africa’s producer price inflation eased to 5.0% year-on-year in August 2026, but persistent fuel and energy shocks continue to place pressure on the economy and keep inflation well above the South African Reserve Bank’s new 2%–4% target range. Although the pace of price increases has slowed, rising costs in petroleum, chemicals, metals, machinery, and intermediate goods, alongside elevated mining costs, suggest that inflationary pressures are still filtering through to businesses and consumers. With consumer inflation at 4.4% and the Reserve Bank having raised interest rates by 25 basis points, this report examines what the latest PPI trends mean for South Africa’s inflation outlook, interest-rate decisions, and the cost pressures likely to shape the economy in the months ahead.
When the South African Reserve Bank unexpectedly tightened monetary policy by 25 basis points to 7.25%, pushing the prime lending rate to 10.75%, it aimed to anchor inflation against imported oil shocks, but at what cost to an already bleeding real economy? With South Africa’s GDP contracting by 0.2%, unemployment climbing to 33.6%, and mining and manufacturing output in reverse, our economic challenge is not an overheated consumer base, but a severe supply-side squeeze. Raising the cost of capital cannot lower global crude prices; instead, it delivers a direct hit to strained household balance sheets and further stifles already anaemic Gross Fixed Capital Formation (GFCF). Dive into the full analysis to unpack why orthodox monetary tools miss the mark in an economy rationing out of necessity, what Governor Lesetja Kganyago’s latest guidance reveals about the interest rate path ahead, and how corporate leaders and investors must position their capital to navigate South Africa’s “higher-for-longer” reality.
South Africa’s August 2026 inflation data present a complex outlook: headline CPI rose to 4.4%, remaining below market expectations yet above the upper limit of the inflation target range, while services inflation continued to climb, and fuel and transport costs exerted further pressure on households and businesses. With the economy contracting, international oil prices rising and global uncertainties, including Middle East tensions and tariff disputes, continuing to weigh on the rand and domestic prices, attention is now focused on the South African Reserve Bank’s next interest-rate decision. Read the full report for an analysis of the factors driving inflation, the risks facing the economy and what the latest developments could mean for consumers, businesses and monetary policy in the months ahead.