Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
September 14, 2026

South African Economic Performance – GDP, Economic growth and Inflation for 2026Q2
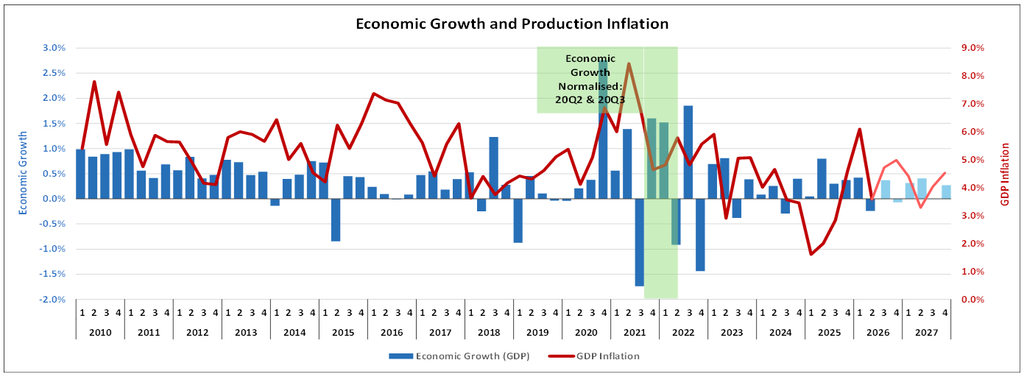
South Africa’s economy faced renewed pressure in the second quarter of 2026, contracting by 0.2% amid high input costs, elevated fuel prices and challenging global conditions. While sectors such as agriculture and finance showed resilience, continued weakness in manufacturing, mining and trade highlights the structural challenges facing the economy. With unemployment remaining elevated and inflationary pressures still a concern, policy clarity, infrastructure investment and improved business confidence will be critical to supporting sustainable economic growth in the months ahead.

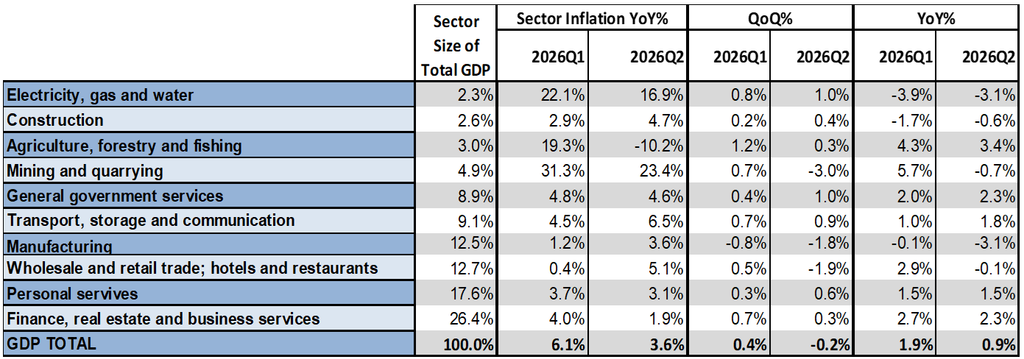
The South African economy contracted by 0.2% in the second quarter of 2026, in line with market expectations. This contraction indicates difficult market conditions and high input costs, especially fuel, which weighed on economic output for the second quarter of 2026.

Out of the ten sectors, seven experienced annual growth. Notably, the Agricultural sector grew by 3.4% in the second quarter, despite facing US tariffs on imports from South Africa. Conversely, the Manufacturing sector saw a further contraction of 3.1%, following a revised 0.1% decline in the first quarter of 2026; this was further compounded by decreases in the Mining and Trade sectors of 0.7% and 0.1%, respectively. The Finance sector grew by 2.3%, indicating some resilience despite higher market interest rates at this stage.

The contraction in economic output does not bode well for an already high unemployment rate of 33.6% in the second quarter of 2026. Slower economic growth only further exacerbates the unemployment crisis South Africa faces, especially youth unemployment, which stands at around 63% at this stage. However, there remains cautious optimism for the rest of the year, despite higher energy prices, conflicts in the Middle East, and ongoing trade tensions affecting South Africa. There is no load-shedding, and interest rates have remained stable at the SARB’s July 2026 Monetary Policy Committee (MPC) meeting.  High international oil prices and imported inflation however remain of concern of the Bank, as imported inflation will move through the economy via price escalations in the transport and logistics sector as a result of higher international oil prices due to the ongoing conflict in the Middle East at this stage. are lower, albeit with a 25-basis-point rise at the end of May. The inflation rate is above 4.0%, the upper limit of the South African Reserve Bank’s new target range, suggesting the Reserve Bank will monitor price inflation like a hawk and may increase interest rates at the next MPC meeting on the 23rd of September.

Nonetheless, businesses continue to face challenges, making it imperative for the government to provide policy clarity going forward, as some progress is being made on infrastructure-related challenges related to rail and port facilities at this stage of previously announced structural reforms. These reforms, alongside government infrastructure investments outlined in the February 2026 budget, could be the catalyst needed for sustained growth this year. It is important to mention that the AGOA agreement has only been extended until the end of 2027, and South Africa’s potential expulsion from it could jeopardise businesses exporting to the United States. Addressing these critical issues is essential for bolstering business confidence, which is crucial for driving substantial economic growth in the forthcoming months – a vital need that South Africa cannot afford to overlook at this point.


More Coverage

What Hong Kong’s 24/7 Tokenised Deposit Pilot Means for South African Banking & Capital Markets. Today’s announcement by the Hong Kong Monetary Authority, launching live 24/7 interbank settlement of tokenised commercial bank deposits backed by central bank money, marks a pivotal transition away from speculative crypto debates toward true institutional financial convergence. In our latest market analysis, we unpack how uniting commercial bank balance sheets with programmable blockchain rails eliminates trapped working capital, cuts reconciliation friction, and resolves the structural limitations of conventional operating hours. Crucially for South Africa, we examine the practical opportunities this shift creates to modernise corporate treasury, deepen secondary liquidity for private credit, and solidify the Rand’s role as the primary settlement gateway for intra-African trade under the AfCFTA, while highlighting where domestic regulatory and payments infrastructure must now transition from sandbox trials to live wholesale deployment.
Despite Binance confirming that it has replenished or covered 95% of the $6.36 billion stolen in last week’s historic cyberattack, verified market data reveals that customers pulled an extraordinary $3.64 billion in net outflows (processing $4.65 billion in gross withdrawals against $1.01 billion in deposits) within hours of withdrawal rails reopening on Sunday, 1 November. In my latest opinion piece, “Binance Replaced the Billions. So Why Are Investors Still Leaving?”, I unpack the critical economic disconnect between balance-sheet solvency, operational liquidity, and investor confidence, demonstrating why corporate treasury bailouts and functioning redemption queues cannot cure the psychological erosion caused by breached custodial architecture. For South Africa’s financial institutions and regulators (SARB and FSCA), these events, compounded by Polymarket’s simultaneous third-party vendor compromise, serve as an urgent wake-up call: domestic fintechs lack multi-billion-dollar treasury buffers, making statutory bankruptcy-remote custody, continuous on-chain proof-of-reserves, and real-time public-private threat circuit breakers essential if South Africa is to turn institutional trust into its greatest competitive economic moat.
The unprecedented security shocks that struck global digital asset markets this week, most notably an estimated $6.36 billion drain across Binance wallets attributed to state-backed cyber syndicates and a client-side vendor intrusion at Polymarket, deliver a blunt reality check to the financial sector: base-layer blockchain mathematics did not fail, but platform custody, access controls, and outsourced third-party software did. In my latest opinion piece, “The Billion-Dollar Wake-Up Call: Why Digital Finance Must Put Security Before Innovation”, I examine why Silicon Valley’s rapid feature velocity has dangerously outrun institutional governance, and why ad hoc balance-sheet reimbursements cannot substitute for fiduciary resilience. For South Africa’s banking, fintech, and regulatory leaders, these breaches highlight the urgency of tightening software supply-chain audits, mandating distributed multi-party custody, and deploying real-time threat coordination, presenting a strategic opportunity for South Africa to leverage institutional trust and rigorous oversight as our primary competitive edge in attracting long-term global digital investment.
Producer price inflation accelerated to 6.2% in September 2026, as higher fuel and energy costs continued to ripple through the economy. Although some cost increases have eased, producer prices remain above the South African Reserve Bank’s new target range, adding to concerns about consumer inflation and the outlook for interest rates. Read the full report for a closer look at the main cost pressures across manufacturing, mining and agriculture—and what they could mean for South African households and businesses in the months ahead.
Credit demand in South Africa continued to grow in September 2026, but fell short of market expectations as households and businesses faced higher interest rates, rising living costs and persistently high debt levels. While mortgage advances and fixed-asset credit picked up, the property market’s recovery remains fragile, and consumers continue to rely on short-term borrowing to manage expenses. With inflation above the target range and energy and fuel costs adding to price pressures, the latest interest rate hike raises fresh questions about the outlook for credit and the wider economy. Read the full report for a closer look at the trends shaping borrowing across the country.