Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
Producer price inflation accelerated to 6.2% in September 2026, as higher fuel and energy costs continued to ripple through the economy. Although some cost increases have eased, producer prices remain above the South African Reserve Bank’s new target range, adding to concerns about consumer inflation and the outlook for interest rates. Read the full report for a closer look at the main cost pressures across manufacturing, mining and agriculture—and what they could mean for South African households and businesses in the months ahead.

Producer Price Inflation – September 2026
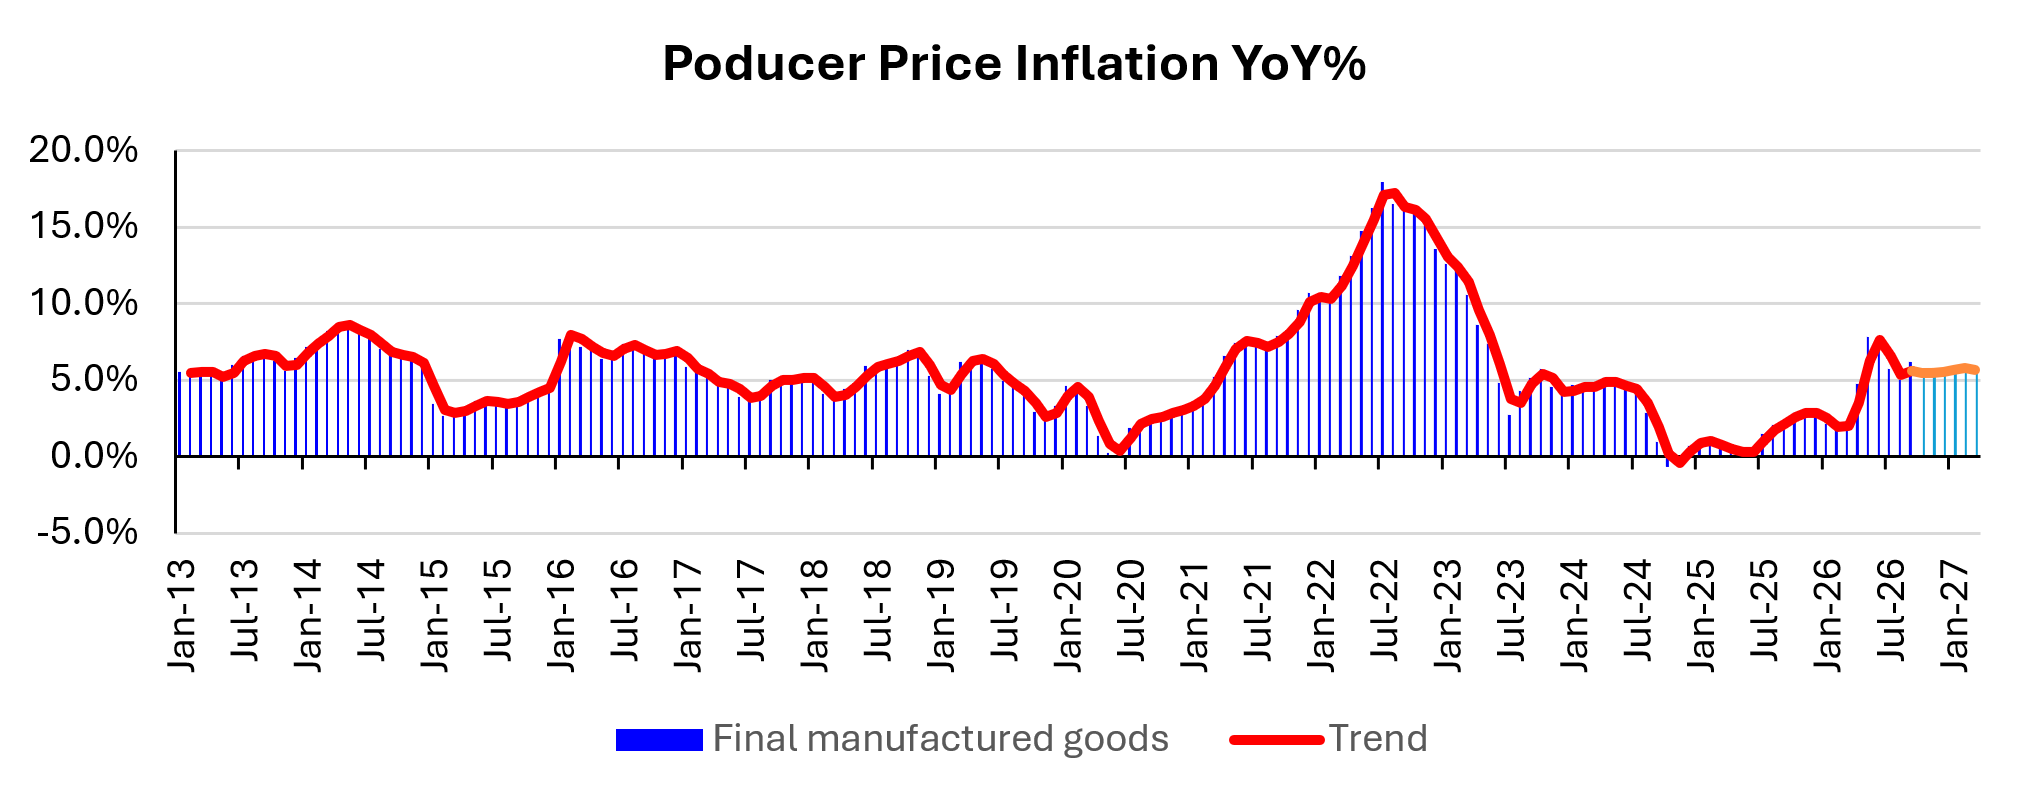
Chart of South African producer price inflation for final manufactured goods, year on year, from January 2013 to September 2026, with trend line and forecast to 2027
MoM % YoY %
Aug-26Sept-26Aug-26Sept-26
Final manufactured goods-0.4%1.0%5.0%6.2%
Food products, beverages and tobacco products-0.3%0.0%1.2%1.2%
Coke, petroleum, chemical, rubber and plastic products5.4%11.8%13.6%19.1%
Petrol-12.3%8.0%7.3%16.2%
Diesel-0.2%-0.9%5.4%4.5%
Transport equipment-0.5%0.0%-1.7%-1.0%
Motor vehicles1.5%-0.3%5.9%3.8%
Parts for transport equipment-0.5%0.0%-1.7%-1.0%
Electricity and water-1.7%-17.7%7.8%8.4%
Electricity-2.0%-20.5%8.5%8.4%
Water0.0%0.0%8.3%8.3%

In September 2026, producer price inflation rose to 6.2% year on year, from 5.0% in August. Fuel-price shocks continued to feed through the economy, pushing up the prices of goods leaving the factory gate. Producer prices increased by 1.0% month on month in September. The annual increase was driven mainly by higher costs in the following categories:

  • Coke, petroleum, chemical, rubber and plastic products: Prices rose by 19.1%, contributing 4.1 percentage points to annual producer price inflation.
  • Metals, machinery, equipment and computing equipment: Prices increased by 3.4% year on year, contributing 0.5 of a percentage point.

The cost of intermediate goods rose by 7.8%, following an 8.8% increase in August 2026. This suggests that inflationary pressure remains, although the rate of increase has eased slightly. These increases still exceed the South African Reserve Bank’s (SARB) new inflation target range of 2% to 4%. Annual growth continues to be affected by higher fuel and energy prices linked to the conflict in the Middle East and the subsequent closure of the Strait of Hormuz.

In the primary sector, mining costs rose by 7.3% in September, matching the increase recorded in August. Costs in the agriculture sector increased by 2.5%.

Overall, producer price inflation remains above the SARB’s upper target, although the rate of increase in producer prices for final manufactured goods has slowed. This may put further pressure on consumer inflation and inflation expectations in South Africa in the short- to medium-term. Consumer inflation was 4.5% in August, still above the upper end of the new target range. Prices for some intermediate goods, particularly water and electricity, also continue to rise faster than the target range. Current figures suggest that consumer inflation is likely to remain elevated in the short- to medium-term as energy price shocks continue to ripple through the economy.

The Reserve Bank has raised the interest rate by 25 basis points. It will continue to assess inflation expectations using both the Consumer Price Index (CPI) and the Producer Price Index (PPI), as price stability remains central to its interest-rate decisions.


More Coverage

Producer price inflation accelerated to 6.2% in September 2026, as higher fuel and energy costs continued to ripple through the economy. Although some cost increases have eased, producer prices remain above the South African Reserve Bank’s new target range, adding to concerns about consumer inflation and the outlook for interest rates. Read the full report for a closer look at the main cost pressures across manufacturing, mining and agriculture—and what they could mean for South African households and businesses in the months ahead.
Credit demand in South Africa continued to grow in September 2026, but fell short of market expectations as households and businesses faced higher interest rates, rising living costs and persistently high debt levels. While mortgage advances and fixed-asset credit picked up, the property market’s recovery remains fragile, and consumers continue to rely on short-term borrowing to manage expenses. With inflation above the target range and energy and fuel costs adding to price pressures, the latest interest rate hike raises fresh questions about the outlook for credit and the wider economy. Read the full report for a closer look at the trends shaping borrowing across the country.
Summary: Economic Insight: Why SA’s falling liquidation numbers hide a sharper corporate story “While Statistics South Africa’s September 2026 data shows an encouraging 12.3% year-on-year drop in total liquidations (and a 17.0% reduction for Q3), a closer inspection of the filings reveals a critical corporate divergence: voluntary business closures fell by 18.5%, but compulsory, court-ordered liquidations surged by 52.0% (and more than doubled for companies alone from 15 to 31 cases). This indicates that while panic-driven owner exits have peaked, creditor forbearance has ended, with banks and suppliers actively enforcing balance-sheet discipline. Paired with elevated business confidence near post-2011 highs (SACCI BCI at 134.3) alongside persistent operational margin pressure from record fuel and energy tariffs, corporate South Africa is not in an outright boom, but rather a ‘Great Repricing’, creating a compelling deployment window for private equity, turnaround capital, and structured private credit to back resilient operators and consolidate fragmented sectors.
Why Rising Global Food Prices Won’t Guarantee Prosperity for SA Farmers While international headlines react to the World Bank’s newly released Commodity Markets Outlook forecasting a 10%+ surge in global food commodity prices and sharp energy increases, South African commercial producers are navigating an acute margin squeeze that challenges popular market assumptions. Caught between domestic export parity pricing following a bumper 17.69-million-tonne harvest and double-digit surges in imported diesel and fertiliser benchmarks, local farmers face shrinking real returns despite elevated global retail food inflation. This macro paradox explains the recent Crop Estimates Committee (CEC) figures, where producers slashed intended maize plantings by 12.4% while pivoting aggressively into lower-capex sunflower seed, offering vital lessons for investors seeking sustainable returns and wealth preservation in high-conviction agricultural value chains. (Full opinion piece and press release attached).
Record Harvest, Rising Risk: Why SA Farmers Are Rethinking Maize? While South Africa’s forecast record commercial maize harvest of roughly 17.69 million tonnes suggests agricultural strength on paper, the Crop Estimates Committee’s 2027 summer-crop planting intentions reveal a sharp, defensive shift: total intended maize plantings are down 12.4% (−337,000 hectares), led by an 18.2% plunge in white maize, while sunflower seed has surged by 44.6% (+254,500 hectares). This divergence highlights a classic commodity paradox: record volumes have compressed local SAFEX prices toward export parity while input costs remain sticky, eroding farm-gate gross margins and prompting producers to reallocate capital into sunflowers to lower upfront working capital outlay and hedge against late-season climatic volatility. For agricultural financiers and private capital, the key lesson is clear: national crop volume does not equal farm profitability, and long-term value preservation depends on balance-sheet agility, crop diversification, and downstream beneficiation rather than sheer top-line production.