Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
September 15, 2026

South African Gold and Foreign Exchange Reserves for August 2026
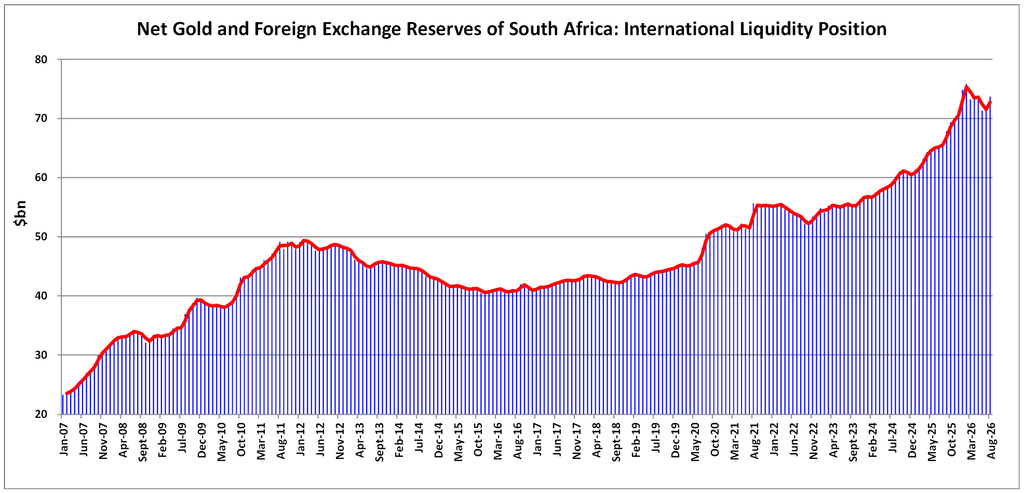
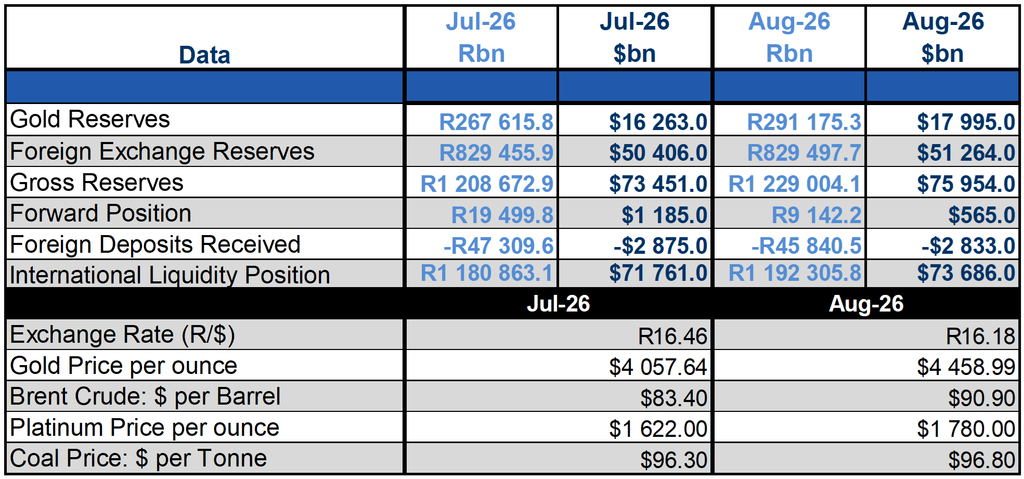
South Africa’s international liquidity position strengthened in August 2026, with net gold and foreign exchange reserves rising by USD 1,9 billion as the rand gained nearly 30c against the US dollar and the gold price climbed to USD 4 460/oz, some 30% higher than a year earlier. Yet beneath these encouraging headline figures lies a far more complex picture: the ongoing conflict in the Middle East and tensions around the Strait of Hormuz are keeping oil prices elevated, while shifting US tariff measures, a one-year AGOA extension and the Federal Reserve’s decision to hold rates steady all point to continued volatility for the rand. With the South African Reserve Bank’s third-quarter interest rate decisions hanging in the balance, this report unpacks what these commodity and currency movements mean for inflation, the mining sector and South Africa’s economic outlook for the remainder of the year.

South Africa’s international liquidity position, measured by net gold and foreign exchange reserves, improved in both US dollar and rand terms in August 2026. According to the South African Reserve Bank (SARB), the rand strengthened by nearly 30c against the US dollar between July and August, despite the ongoing conflict in the Middle East.

Reserves rose by USD 1,9 billion in August, following an increase of USD 423 million in July 2026.

Gold continues to support reserves

The gold price remains elevated. It rose by just over USD 400/oz during August, from USD 4 057/oz in July to USD 4 460/oz, and is still around 30% higher than a year earlier. This sustained strength in the gold price has been a key factor supporting South Africa’s reserves from January through August, against the backdrop of the conflict in the Middle East.

In US dollar terms, foreign reserves increased in August compared with the previous month. The SARB also purchased US dollars in open market operations, partly in response to a slightly stronger rand and a slightly weaker dollar, which influenced the country’s net international liquidity position at the time.

Why commodity trends matter

Key commodities such as gold, oil, platinum and coal provide valuable insight into the health of South Africa’s mining sector and the inflation outlook. Monitoring these trends is essential for assessing inflation prospects, particularly given ongoing international developments and potential trade restrictions with the United States following the tariff measures introduced in August.

Implications for interest rates and the rand

Inflation expectations will shape the SARB’s interest rate decisions in the third quarter of 2026, especially amid the Middle East conflict and tensions around the Strait of Hormuz. While the rand has been relatively stable and slightly stronger of late, oil prices remain higher than at the start of 2026, which adds to inflationary pressure.

Several external factors could also increase market volatility:

  • Continued global geopolitical tensions
  • Possible changes to trade agreements, including the African Growth and Opportunity Act (AGOA), which the US administration has extended by one year
  • The reduction of the 30% reciprocal tariffs to 12,5% for now, after the US Supreme Court ruled that the 30% tariffs were unconstitutional and had to be withdrawn
  • The US Federal Reserve’s decision to keep interest rates unchanged at its announcement on 29 July 2026

Given these developments, the rand may continue to experience short-term fluctuations despite its recent appreciation against the US dollar. This could influence South Africa’s economic outlook for the remainder of the year.


More Coverage

South Africa’s mining sector is facing mounting pressure, with production falling 7.5% in July 2026 after a revised 4.3% decline in June, while the rolling three-month contraction reached 5.5% and nominal mining sales dropped 5.6%. Sharp declines in iron ore, coal, PGMs, gold, manganese, and nickel highlight the sector’s vulnerability, compounded by job losses, rising fuel and energy costs, policy uncertainty, property rights concerns, and growing trade barriers. Yet mining remains indispensable to the economy, supporting approximately 450,000 jobs, generating foreign exchange and contributing to growth. With elevated gold prices and temporary tariff exemptions offering limited relief, this report examines the forces reshaping South Africa’s mining industry—and whether these bright spots can withstand the sector’s deepening structural and geopolitical challenges.
South Africa’s economy faced renewed pressure in the second quarter of 2026, contracting by 0.2% amid high input costs, elevated fuel prices and challenging global conditions. While sectors such as agriculture and finance showed resilience, continued weakness in manufacturing, mining and trade highlights the structural challenges facing the economy. With unemployment remaining elevated and inflationary pressures still a concern, policy clarity, infrastructure investment and improved business confidence will be critical to supporting sustainable economic growth in the months ahead.
South Africa’s latest trade figures reveal a mixed economic picture: although the country recorded a R20.1 billion trade surplus in July 2026, export growth continues to rely heavily on raw materials such as metals, gold, and minerals, while imports remain concentrated in higher-value products including vehicles, chemicals, and machinery. Exports rose 8.3% over the first seven months of the year, outpacing the 6.0% increase in imports and highlighting subdued domestic demand among households and businesses. However, with higher fuel prices, imported inflation, and a potentially tighter monetary policy, including another expected interest-rate increase, economic activity and demand could weaken further in the months ahead. The full report examines what these trends mean for South Africa’s trade performance, domestic consumption, and growth prospects for the remainder of 2026.
South Africa’s latest inflation figures provide some welcome relief, but a renewed surge in global oil prices threatens to undermine this progress. With fuel prices rising sharply due to external geopolitical and supply-side pressures, the debate over whether the SARB should respond with higher interest rates has become increasingly important. This article argues that raising rates to combat imported inflation would risk doing more harm than good—placing further pressure on households, businesses and investment in an economy already facing weak growth, high unemployment and significant industrial challenges.
Private sector credit growth remained resilient in July 2026, reflecting continued demand for financing despite elevated living costs and renewed interest rate uncertainty. While overall credit extension continues to benefit from the rate-cutting cycle that began in late 2024, subdued property activity and rising household reliance on short-term credit highlight ongoing pressure on consumers and businesses.