Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
September 16, 2026

A view on Demand in the Economy: Retail Sales performance – July 2026 Data
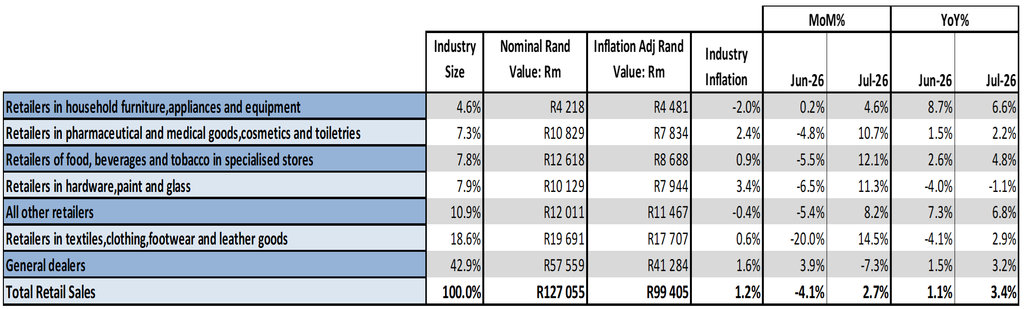
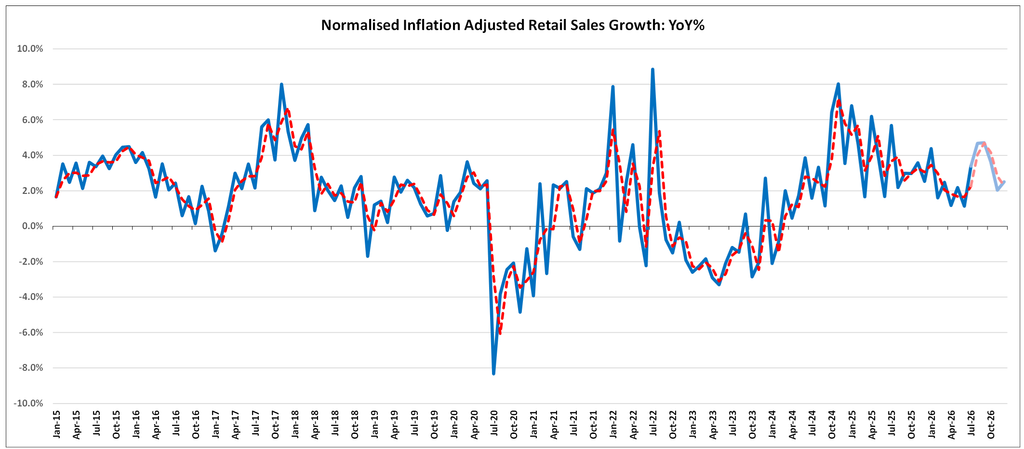
South Africa’s retail sector delivered a striking surprise in July 2026, with sales climbing 3.4% against market expectations of a 3.0% contraction, but the story beneath that headline number is far more nuanced than it first appears. This report unpacks the fragile balancing act facing local households: inflation easing to 4.3% yet still stubbornly above the SARB’s new 2–4% target band, administered prices and utility costs rising by more than 4.0%, wage growth lagging behind severe fuel shocks, and the lingering effect of May’s 25-basis-point rate hike prompted by inflationary pressures well beyond Pretoria’s control. We examine why business confidence firmed (SACCI up from 123.5 to 125.4) while consumer sentiment slumped sharply (FNB/BER down from -7 to -19), which categories, from “other retailers” to general dealers and household goods, actually carried the growth, and what the extension of AGOA to end-2027 means now that fresh visa tensions between Washington and Pretoria have placed South Africa’s eligibility squarely under the microscope. Read the full report to understand whether this recovery has the legs to survive higher fuel prices, a possible second rate increase, and a second-quarter contraction in economic activity — or whether July’s good news was simply borrowed from the easing cycle of 2024/25.

In July 2026, retail sales in South Africa rose by 3.4%, well above the 3.0% contraction market analysts anticipated. This growth underscores a continued but fragile recovery in consumer demand.

Households, however, still face several challenges. The South African Reserve Bank and consumer inflation data point to ongoing increases in administered prices and housing and utility costs, each rising by more than 4.0%, with overall inflation reaching 4.3% in July. Wage growth is rising but not fast enough to fully offset the severe fuel shocks the South African economy faced over the last couple of months. Uncertainties, however, remain, including concerns about a contraction in economic activity in the second quarter of 2026, while uncertainties in international trade, including new diplomatic tensions between Washington and Pretoria following the new visa restriction policy against South Africans, are increasing uncertainty within the domestic economy. Luckily, the African Growth and Opportunity Act (AGOA) was extended to the end of 2027, although the US still reserves the right to evaluate individual countries regarding their eligibility for participation in the AGOA arrangement, which places South Africa squarely in the sights of US lawmakers given the new US visa policy regarding South Africans with political connections.

July’s 3.4% gain continues the recovery trend from April 2025 to July 2026, even though consumer demand remains fragile but stable at this stage. The July expansion in retail sales is likely still supported by interest-rate cuts and monetary easing implemented between September 2024 and November 2025, but higher fuel costs in recent months will weigh heavily on consumer spending in the months to follow, not to mention the interest rate increase that was done during the May meeting of the MPC.  The interest rate increase by the SARB was intended to “combat rising inflation and inflation expectations”, even though these inflationary pressures originated outside South Africa and were completely beyond the SARB’s control in Pretoria. The South African Chamber of Commerce and Industry (SACCI) recorded an increase in business confidence (the index rising from 123.5 in June to 125.4 in July 2026). The FNB/BER consumer confidence index, however, declined from the first to the second quarter of 2026, from -7 in 2026Q1 to -19 in 2026Q2, indicating that higher interest rates coupled with higher fuel prices are weighing on consumer sentiment in the market. The fall in consumer sentiment in South Africa during the second quarter simply highlights that consumer caution remains persistent amid underlying market uncertainties. Although inflation came down slightly during July, from 5.0% in June to 4.3% in July, it remains outside the upper limit of the SAEB’s new target range of 2- to 4%, which means that the Reserve Bank is likely to raise rates once again should inflation remain persistently outside the target range.  July’s retail growth was driven by:

  • Other retailers: up 6.8%, contributing 0.8 percentage points
  • General dealers up 3.2%, contributing 1.3 percentage points
  • Retailers in household furniture, appliances and equipment rising by 2.9% and contributing 0.5 percentage points and
  • Retailers in food, beverages and tobacco in specialised stores up 4.8%, contributing 0.4 percentage points

The sustained momentum since July suggests a steady, if cautious, recovery. Interest-rate cuts from September 2024 to November 2025 have eased some household financial pressure and still support demand recovery at this stage, but the 25-basis-point interest-rate increase in May, international developments, higher fuel prices, and a possible further increase in interest rates may weigh on consumer demand going forward.


More Coverage

What Hong Kong’s 24/7 Tokenised Deposit Pilot Means for South African Banking & Capital Markets. Today’s announcement by the Hong Kong Monetary Authority, launching live 24/7 interbank settlement of tokenised commercial bank deposits backed by central bank money, marks a pivotal transition away from speculative crypto debates toward true institutional financial convergence. In our latest market analysis, we unpack how uniting commercial bank balance sheets with programmable blockchain rails eliminates trapped working capital, cuts reconciliation friction, and resolves the structural limitations of conventional operating hours. Crucially for South Africa, we examine the practical opportunities this shift creates to modernise corporate treasury, deepen secondary liquidity for private credit, and solidify the Rand’s role as the primary settlement gateway for intra-African trade under the AfCFTA, while highlighting where domestic regulatory and payments infrastructure must now transition from sandbox trials to live wholesale deployment.
Despite Binance confirming that it has replenished or covered 95% of the $6.36 billion stolen in last week’s historic cyberattack, verified market data reveals that customers pulled an extraordinary $3.64 billion in net outflows (processing $4.65 billion in gross withdrawals against $1.01 billion in deposits) within hours of withdrawal rails reopening on Sunday, 1 November. In my latest opinion piece, “Binance Replaced the Billions. So Why Are Investors Still Leaving?”, I unpack the critical economic disconnect between balance-sheet solvency, operational liquidity, and investor confidence, demonstrating why corporate treasury bailouts and functioning redemption queues cannot cure the psychological erosion caused by breached custodial architecture. For South Africa’s financial institutions and regulators (SARB and FSCA), these events, compounded by Polymarket’s simultaneous third-party vendor compromise, serve as an urgent wake-up call: domestic fintechs lack multi-billion-dollar treasury buffers, making statutory bankruptcy-remote custody, continuous on-chain proof-of-reserves, and real-time public-private threat circuit breakers essential if South Africa is to turn institutional trust into its greatest competitive economic moat.
The unprecedented security shocks that struck global digital asset markets this week, most notably an estimated $6.36 billion drain across Binance wallets attributed to state-backed cyber syndicates and a client-side vendor intrusion at Polymarket, deliver a blunt reality check to the financial sector: base-layer blockchain mathematics did not fail, but platform custody, access controls, and outsourced third-party software did. In my latest opinion piece, “The Billion-Dollar Wake-Up Call: Why Digital Finance Must Put Security Before Innovation”, I examine why Silicon Valley’s rapid feature velocity has dangerously outrun institutional governance, and why ad hoc balance-sheet reimbursements cannot substitute for fiduciary resilience. For South Africa’s banking, fintech, and regulatory leaders, these breaches highlight the urgency of tightening software supply-chain audits, mandating distributed multi-party custody, and deploying real-time threat coordination, presenting a strategic opportunity for South Africa to leverage institutional trust and rigorous oversight as our primary competitive edge in attracting long-term global digital investment.
Producer price inflation accelerated to 6.2% in September 2026, as higher fuel and energy costs continued to ripple through the economy. Although some cost increases have eased, producer prices remain above the South African Reserve Bank’s new target range, adding to concerns about consumer inflation and the outlook for interest rates. Read the full report for a closer look at the main cost pressures across manufacturing, mining and agriculture—and what they could mean for South African households and businesses in the months ahead.
Credit demand in South Africa continued to grow in September 2026, but fell short of market expectations as households and businesses faced higher interest rates, rising living costs and persistently high debt levels. While mortgage advances and fixed-asset credit picked up, the property market’s recovery remains fragile, and consumers continue to rely on short-term borrowing to manage expenses. With inflation above the target range and energy and fuel costs adding to price pressures, the latest interest rate hike raises fresh questions about the outlook for credit and the wider economy. Read the full report for a closer look at the trends shaping borrowing across the country.