September 23, 2026

Consumer Inflation – August 2026
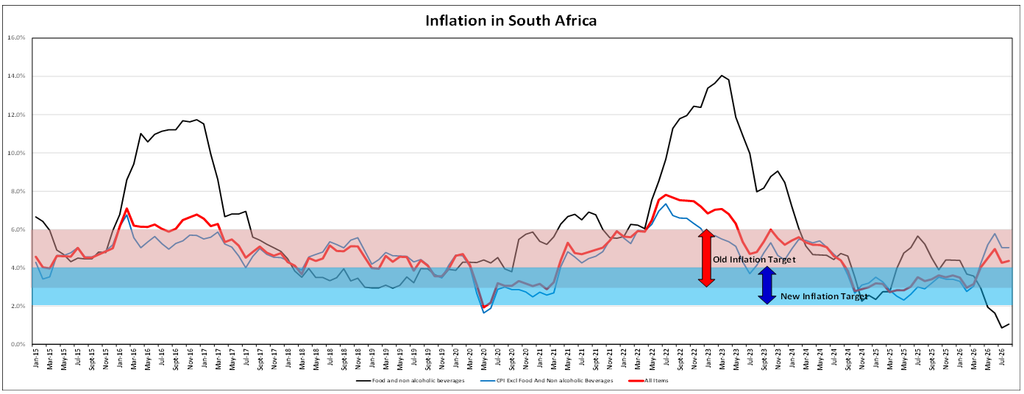
South Africa’s August 2026 inflation data present a complex outlook: headline CPI rose to 4.4%, remaining below market expectations yet above the upper limit of the inflation target range, while services inflation continued to climb, and fuel and transport costs exerted further pressure on households and businesses. With the economy contracting, international oil prices rising and global uncertainties, including Middle East tensions and tariff disputes, continuing to weigh on the rand and domestic prices, attention is now focused on the South African Reserve Bank’s next interest-rate decision. Read the full report for an analysis of the factors driving inflation, the risks facing the economy and what the latest developments could mean for consumers, businesses and monetary policy in the months ahead.

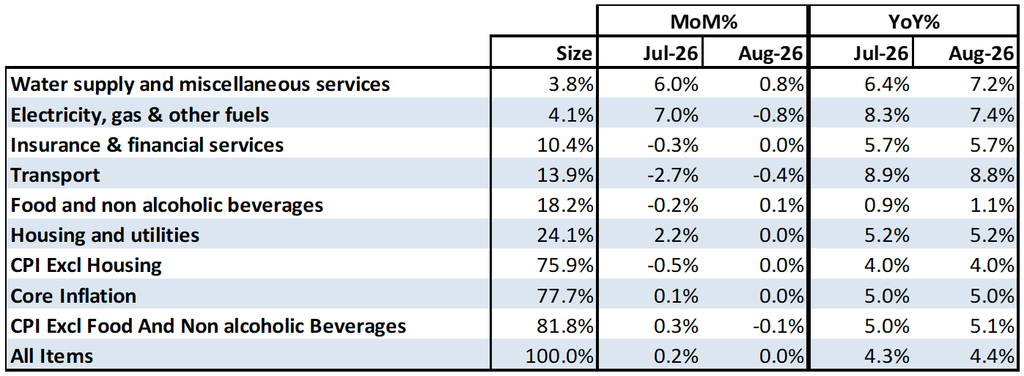
In August 2026, the Consumer Price Index (CPI) increased by 4.4% year on year, slightly higher than the 4.3% recorded in July but below the market expectation of 4.5% for the month under review. The increase in consumer prices was mainly driven by:

  • Housing and utilities: Increased by 5.2%, contributing 1.3 percentage points.
  • Transport: Increased by 8.8%, contributing 1.2 percentage points.
  • Insurance and financial services: Increased by 5.7%, contributing 0.6 percentage points.

Compared with August 2025, goods inflation increased by 3.3% in August 2026, down slightly from the 3.4% recorded in July. Services inflation, meanwhile, rose from 5.0% in July to 5.1% in August.

Goods inflation now falls within the South African Reserve Bank’s (SARB’s) new target range of 2% to 4%, while services inflation remains above the upper limit of 4.0%. This suggests that inflation is currently entering the economy primarily through the services channel.

The continued rise in inflation is eroding household purchasing power in South Africa. In addition, interest rates and fuel prices have not returned to their pre-Middle East conflict levels. As a result, many consumers and businesses are increasingly relying on short-term credit, leaving them vulnerable to changes in interest rates, exchange rates, global oil prices, and import costs. These factors, in turn, place further pressure on domestic prices.

These vulnerabilities have been exacerbated by the ongoing conflict in the Middle East and the significant increase in fuel prices between April and May. The recent escalation of the conflict has led to another rise in international oil prices, which does not bode well for fuel price reductions in the coming month.

Following its January 2026 meeting, the Monetary Policy Committee (MPC) decided to keep interest rates unchanged after considering the latest inflation figures and economic forecasts. However, the MPC increased the policy rate by 25 basis points at the end-of-May meeting in response to the inflationary spike arising from the Middle East conflict and the rise in international oil prices observed during April and May.

At its July meeting, the Reserve Bank again kept interest rates unchanged, contrary to market expectations. By then, financial markets had largely priced in a 25-basis-point increase. The MPC is scheduled to announce another interest-rate decision today, with market expectations split between a 25-basis-point increase and an unchanged decision. This uncertainty has been heightened by the 0.2% contraction in the South African economy during the second quarter of 2026.

Elevated fuel and transport costs are expected to continue influencing inflation expectations, particularly following the 4.4% inflation recorded in August, which remains above the upper limit of the target range. The Bank’s cautious approach is intended to maintain price stability amid ongoing domestic and international uncertainties. These include the higher tariffs imposed by the United States on South African exports, which have negatively affected the manufacturing sector, as reflected in the second-quarter 2026 GDP data. The latest unemployment, mining, and manufacturing data have also contributed to uncertainty about the economic outlook.

The increase in international oil prices over the past two weeks, together with inflation coming in below market expectations, may encourage the SARB to keep interest rates unchanged at the upcoming MPC meeting. Previous interest-rate cuts in late 2024, throughout 2025 and again in November 2025 were aimed at stimulating demand by increasing households’ disposable income after interest payments and supporting economic growth. However, rising fuel prices and a tightening monetary-policy stance could limit the extent to which these measures support economic activity.

Despite the 0.2% contraction in the economy during the second quarter of 2026, the Bank remains cautious because of persistent global uncertainties. Inflationary pressures, the US–China tariff dispute and the possibility of further tariffs on BRICS nations could all affect price stability. In addition, the Middle East conflict may keep international oil prices elevated if shipping safety through the Strait of Hormuz cannot be assured and the conflict lasts longer than markets anticipate.

Future interest-rate decisions are likely to take into account moderate inflation within the new target range, weak economic growth, improvements in electricity supply, some positive market sentiment and international tensions affecting oil prices. In conclusion, maintaining price stability and protecting the value of the rand remain key priorities for South Africa as the country navigates the remainder of 2026 amid ongoing international developments and related uncertainties.


More Coverage

Why Stats SA’s Q3 Employment Rebound Masks an Escalating Rural and Informal Crisis While Statistics South Africa’s Q3:2026 Quarterly Labour Force Survey reports an apparent rebound of 101,000 in total employment driven by resilient formal corporate hiring (+268,000, led by finance, manufacturing, and mining), this headline growth conceals a severe structural divergence. Official unemployment rose to 33.7%, drastically missing consensus expectations of 32.5%, while the expanded unemployment rate worsened to 44.0%, driven by demographic expansion outstripping job creation and the near-total blowout of the economy’s traditional safety valves. Over the past year, the informal economy has shed an alarming 485,000 jobs (-12.2% YoY), while private household employment contracted by 68,000 in Q3 alone. Concurrently, primary agriculture shed 34,000 jobs (-3.6% QoQ), with skilled commercial agricultural employment plunging 47.5% YoY amidst emerging El Niño drought risks, depressed business confidence (RMB/BER BCI at 38), and looming trade headwinds from South Africa’s anticipated loss of AGOA market access after 1 January 2027. The attached opinion piece and press release provide an in-depth analysis of what these figures mean for investment strategy, business sentiment, and the structural reforms urgently required to avert deeper rural and informal displacement.
South Africa’s third-quarter 2026 employment figures offer a mixed picture: Manufacturing and Mining added jobs, and employment rose in several provinces, yet unemployment continued to climb and came in well above market expectations. With the working-age population also growing and global trade tensions, Middle East conflict and uncertainty over AGOA adding to the pressure, the latest data raise important questions about the pace and sustainability of job creation. Read the full report for a closer look at what’s driving the numbers, and which sectors and provinces may be most exposed.
With Botswana announcing plans to double its stake in De Beers from 15% to 30% alongside Anglo American’s historic disposal, we have published an executive analysis examining the investment calculus behind this landmark transaction: “Botswana Wants a Bigger Share of De Beers. But Is Bigger Ownership Always Better?” While securing a larger sovereign footprint reasserts domestic resource sovereignty, disciplined capital allocators must weigh whether Gaborone is acquiring a strategic bargain or dangerously compounding national exposure to an industry wrestling with structural disruptions from lab-grown synthetics and muted global luxury demand. Our piece breaks down how institutional investors should evaluate distressed commodity assets, the balance sheet realities of unlisted co-ownership, and what Anglo’s unbundling means for South African portfolios and regional SADC market confidence.
As global financial markets grapple with unprecedented concentration in a handful of mega-cap technology champions, our latest macroeconomic analysis, “The Nvidia Effect: When Global Markets Become Too Dependent on a Few Companies,” examines why uncertainty surrounding a single silicon powerhouse now exerts more systemic influence over global indices than traditional economic indicators. The piece explores how passive ETF capital flows mechanise market vulnerability, why shift-prone investor sentiment triggers severe multiple contractions even when corporate earnings fundamentals remain immaculate, and how South African investors taking capital offshore to hedge local risk have inadvertently fallen into a concentration trap by holding the exact same tech giants across different international feeder funds. We outline actionable, structural strategies for local wealth managers, institutional allocators, and individual investors to unbundle this risk and build authentic portfolio resilience.
The AGOA Reckoning: Weighing the Real Cost to Jobs, Industry, and the Fiscus Following the US administration’s confirmation that South Africa will be removed from the African Growth and Opportunity Act (AGOA) in January 2027, within a 60-day notice period, our latest economic analysis evaluates the severe consequences for the domestic economy. With an estimated 125,000 to 570,000 direct and indirect jobs now on the line, predominantly across automotive manufacturing in the Eastern Cape and agricultural fruit exports in the Western Cape, this trade shock hits an economy where unemployment already sits at an elevated 33.6% (43.8% expanded) and manufacturing contracted by 3.1% in Q2 2026. While Pretoria’s proposed “Plan B” seeks alternative export corridors via the Butterfly Strategy, it ignores the structural reality that Asian export powerhouses like China absorb raw mineral commodities rather than assembled finished goods, even as heavily subsidised Chinese imports continue to erode local industrial capacity. Left unaddressed, this loss of trade preference risks igniting a vicious fiscal transmission loop: triggering steep contractions in PAYE and VAT receipts, ballooning social grant expenditure, elevating sovereign borrowing, and driving up long-term bond yields at the very moment the fiscus was beginning to turn the corner. The attached comprehensive article and press release make the case for urgent, pragmatic economic diplomacy over political posturing to protect our industrial base and sovereign balance sheet.