Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
April 14, 2026

Mining Production and Sales for February 2026
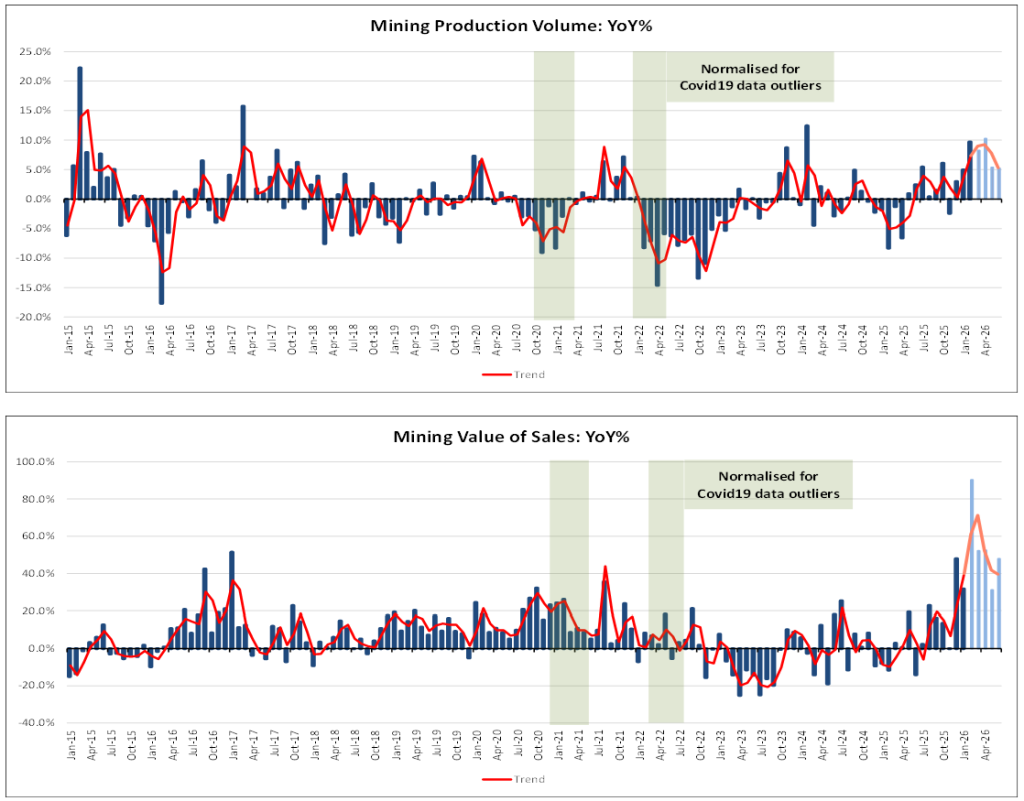
Discover the dynamic shifts within South Africa’s mining sector with our latest analysis. In a remarkable February 2026 performance, mining activities surged by 9.7%, spearheaded by dramatic increases in PGM, chromium ore, manganese, and gold production. Despite a quarterly dip, February’s nominal sales skyrocketed by 58.3%, driven by remarkable gains in platinum and gold. As the backbone of South Africa’s economy, the sector faces evolving global challenges and opportunities, from new US tariff measures to geopolitical tensions affecting global trade and energy prices. Stay ahead with insights into the sector’s resilience and strategic importance. Read the full article to understand the trends shaping South Africa’s economic landscape.

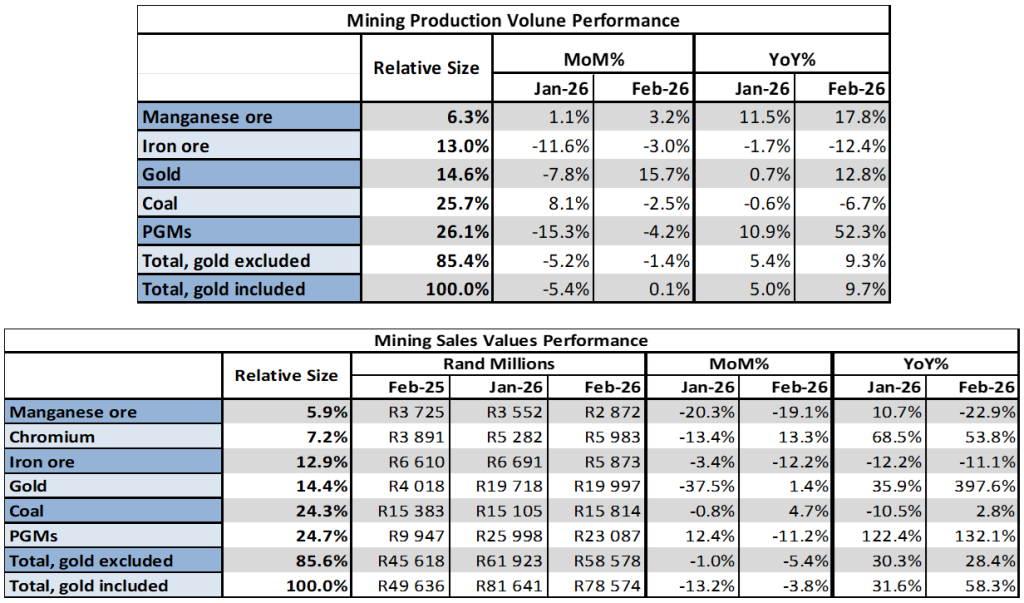
In February 2026, South Africa’s mining activity rose 9.7% following the revised 5.0% increase recorded in January 2026. This growth was predominantly driven by:

  • A 52.3% increase in PGM mining production, which contributed 9.4 percentage points to the overall mining output for the month.
  • A substantial 26.9% rise in chromium ore output, adding another 1.6 percentage points.
  • Manganese production rose by 17.8% during January, while adding 1.5 percentage points towards mining production growth and
  • A 12.8% increase in Gold production, which added an additional 1.3 percentage points to total mining output growth for the month.

For the rolling quarter ending February 2026 compared with the previous rolling quarter, seasonally adjusted mining output decreased by 1.7%. This decline was primarily due to:

  • A 2.5% drop in platinum mining, which decreased total mining production by 0.7 percentage points and
  • Adecrease in Iron ore production, which decreased by 9.7% and, subtracted 1.4 percentage points for the quarter under review.

In February, nominal mining sales rose 58.3%. This positive trend was notably supported by:

  • A 132.1% surge in platinum sales, which added 26.5 percentage points to overall mining sales growth.
  • Another impressive 397% rise in gold sales, contributing 32.2 percentage points.
  • Chromium ore sales, which grew by 53.8%, added another 4.2 percentage points.

The mining sector remains vital to South Africa’s economy, generating foreign exchange and employing approximately 444,000 people, a slight decrease of 5,000 from the previous quarter, according to StatsSA labour statistics for the fourth quarter of 2025. According to the latest GDP data, the sector however contracted by 1.3% from the third to the fourth quarter of 2025, with sector growth of 0.9% projected for the first quarter of 2026. This projected first-quarter growth is encouraging, given the sector’s importance to employment and foreign earnings for the South African economy.

Despite a slight decrease in employment from the previous quarter, the sector’s continued significance is evident. However, challenges persist, including concerns over exports to the US following new tariff measures introduced on 7 August, proposed export tariffs on manganese, and import tariffs on steel exports to the Eurozone. The sector also faces challenges related to the loss of AGOA benefits in September and ongoing issues with the new Mining Charter.

On the international stage, geopolitical tensions between the US and China—marked by trade conflicts and tariff disputes—continue to disrupt global markets and limit trade flows. The current Middle Eastern conflict between the US/Israel, and Iran does not bode well for international oil prices as seen in the notable increase in energy prices at this stage, and may cause some sectors to experience rapid cost increases if the conflict isn’t resolved quickly. Nonetheless, some positive developments, such as the continued temporary exemption of certain mining materials used in steelmaking from high US tariffs, have occurred. This provides some relief for the sector, which remains crucial to South Africa’s economy in terms of employment, foreign exchange, and overall growth.


More Coverage

What Hong Kong’s 24/7 Tokenised Deposit Pilot Means for South African Banking & Capital Markets. Today’s announcement by the Hong Kong Monetary Authority, launching live 24/7 interbank settlement of tokenised commercial bank deposits backed by central bank money, marks a pivotal transition away from speculative crypto debates toward true institutional financial convergence. In our latest market analysis, we unpack how uniting commercial bank balance sheets with programmable blockchain rails eliminates trapped working capital, cuts reconciliation friction, and resolves the structural limitations of conventional operating hours. Crucially for South Africa, we examine the practical opportunities this shift creates to modernise corporate treasury, deepen secondary liquidity for private credit, and solidify the Rand’s role as the primary settlement gateway for intra-African trade under the AfCFTA, while highlighting where domestic regulatory and payments infrastructure must now transition from sandbox trials to live wholesale deployment.
Despite Binance confirming that it has replenished or covered 95% of the $6.36 billion stolen in last week’s historic cyberattack, verified market data reveals that customers pulled an extraordinary $3.64 billion in net outflows (processing $4.65 billion in gross withdrawals against $1.01 billion in deposits) within hours of withdrawal rails reopening on Sunday, 1 November. In my latest opinion piece, “Binance Replaced the Billions. So Why Are Investors Still Leaving?”, I unpack the critical economic disconnect between balance-sheet solvency, operational liquidity, and investor confidence, demonstrating why corporate treasury bailouts and functioning redemption queues cannot cure the psychological erosion caused by breached custodial architecture. For South Africa’s financial institutions and regulators (SARB and FSCA), these events, compounded by Polymarket’s simultaneous third-party vendor compromise, serve as an urgent wake-up call: domestic fintechs lack multi-billion-dollar treasury buffers, making statutory bankruptcy-remote custody, continuous on-chain proof-of-reserves, and real-time public-private threat circuit breakers essential if South Africa is to turn institutional trust into its greatest competitive economic moat.
The unprecedented security shocks that struck global digital asset markets this week, most notably an estimated $6.36 billion drain across Binance wallets attributed to state-backed cyber syndicates and a client-side vendor intrusion at Polymarket, deliver a blunt reality check to the financial sector: base-layer blockchain mathematics did not fail, but platform custody, access controls, and outsourced third-party software did. In my latest opinion piece, “The Billion-Dollar Wake-Up Call: Why Digital Finance Must Put Security Before Innovation”, I examine why Silicon Valley’s rapid feature velocity has dangerously outrun institutional governance, and why ad hoc balance-sheet reimbursements cannot substitute for fiduciary resilience. For South Africa’s banking, fintech, and regulatory leaders, these breaches highlight the urgency of tightening software supply-chain audits, mandating distributed multi-party custody, and deploying real-time threat coordination, presenting a strategic opportunity for South Africa to leverage institutional trust and rigorous oversight as our primary competitive edge in attracting long-term global digital investment.
Producer price inflation accelerated to 6.2% in September 2026, as higher fuel and energy costs continued to ripple through the economy. Although some cost increases have eased, producer prices remain above the South African Reserve Bank’s new target range, adding to concerns about consumer inflation and the outlook for interest rates. Read the full report for a closer look at the main cost pressures across manufacturing, mining and agriculture—and what they could mean for South African households and businesses in the months ahead.
Credit demand in South Africa continued to grow in September 2026, but fell short of market expectations as households and businesses faced higher interest rates, rising living costs and persistently high debt levels. While mortgage advances and fixed-asset credit picked up, the property market’s recovery remains fragile, and consumers continue to rely on short-term borrowing to manage expenses. With inflation above the target range and energy and fuel costs adding to price pressures, the latest interest rate hike raises fresh questions about the outlook for credit and the wider economy. Read the full report for a closer look at the trends shaping borrowing across the country.