Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
September 30, 2026

Producer Price Inflation – Aug 2026
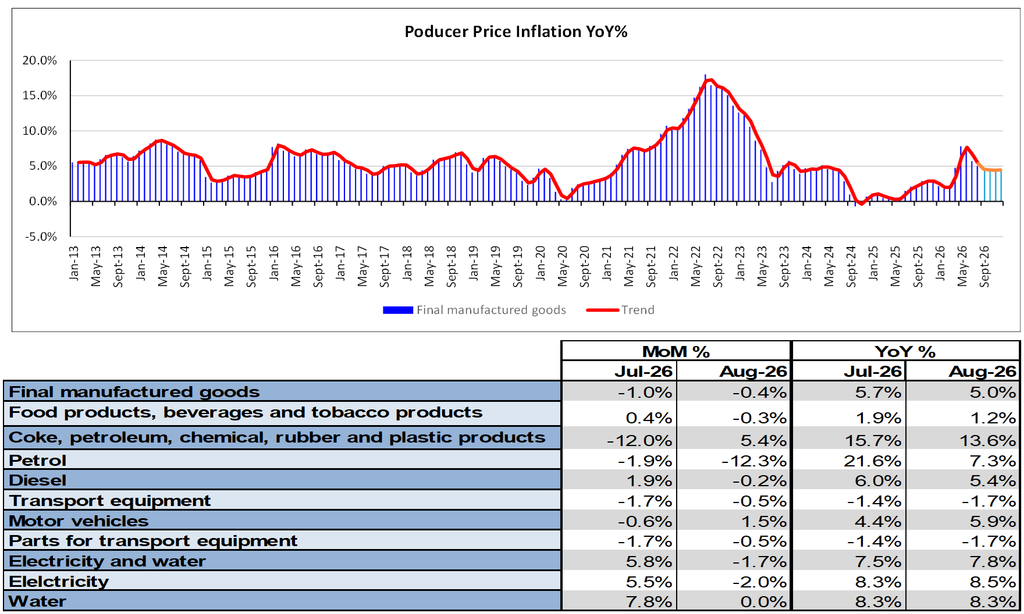
South Africa’s producer price inflation eased to 5.0% year-on-year in August 2026, but persistent fuel and energy shocks continue to place pressure on the economy and keep inflation well above the South African Reserve Bank’s new 2%–4% target range. Although the pace of price increases has slowed, rising costs in petroleum, chemicals, metals, machinery, and intermediate goods, alongside elevated mining costs, suggest that inflationary pressures are still filtering through to businesses and consumers. With consumer inflation at 4.4% and the Reserve Bank having raised interest rates by 25 basis points, this report examines what the latest PPI trends mean for South Africa’s inflation outlook, interest-rate decisions, and the cost pressures likely to shape the economy in the months ahead.

In August 2026, producer price inflation increased by 5.0% year-on-year, down from 5.7% in July, as fuel price shocks continued to trickle through the economy into the prices of goods leaving the factory gate. However, producer inflation decreased by 0.4% monthly during August, while the annual increase was mostly due to cost increases in the following categories:

  • Coke, petroleum, chemical, rubber and plastic products: Increased by 13.6% and contributed 2.9 percentage points,
  • Metals, machinery, equipment and computing equipment: Rose by 3.4% year-on-year while contributing 0.5 of a percentage point.

Production costs for intermediate goods rose by another 8.8% following the 9.8% in July 2026. This indicates that a clear inflationary trend is still ongoing, even though the pace of escalation continues to slow slightly. These increases still greatly exceed the South African Reserve Bank’s (SARB) new inflation target range of 2% to 4%. Annual growth is still significantly influenced by increases in fuel and energy prices resulting from the conflict in the Middle East and the subsequent closure of the Strait of Hormuz.

In the primary sector, mining costs climbed by 7.3% in August, following a 9.6% rise in July. In contrast, the agriculture sector experienced a further 1.8% decline, following a 4.5% decrease the previous month.

Overall, the trend in producer price inflation remains above the SARB’s upper target, albeit at a slower rate of escalation in producer prices for final manufactured goods, which does not bode well for general consumer inflation and inflation expectations in South Africa in the short- to medium-term. Consumer inflation still exceeds the upper band of the new target range, at 4.4% in August. While prices for certain intermediate goods, particularly water and electricity, continue to exceed the target range, current figures suggest consumer inflation will likely remain elevated in the short- to medium-term, as energy price shocks continue to reverberate throughout the economy.

The Reserve Bank has increased the interest rate by 25 basis points and will continue to analyse inflation expectations using both the Consumer Price Index (CPI) and the Producer Price Index (PPI), as price stability remains the key concern for the Bank in making interest rate decisions for South Africa.


More Coverage

South Africa recorded a trade surplus of R20.4 billion in August 2026, as exports continued to outpace imports. Export growth has exceeded import growth over the first eight months of the year, reflecting subdued domestic demand among businesses and consumers. But with higher fuel prices and tighter monetary policy expected to weigh on spending, demand is likely to recover only gradually. Read the full report for a closer look at the trade figures and what they could mean for South Africa’s economy in the months ahead.
South Africa’s credit market is showing surprising resilience, with credit demand rising by 7.5% in August 2026 despite renewed interest-rate pressure, elevated inflation and mounting household costs. While mortgage advances continued to grow, the fragile recovery in the property market highlights the strain caused by subdued investment, high debt levels and rising municipal and energy expenses. At the same time, sluggish instalment credit growth and continued reliance on short-term borrowing reveal how consumers are navigating increasingly difficult financial conditions. With higher oil prices, geopolitical risks and further SARB tightening adding to the pressure, this report examines what the latest credit trends reveal about household finances, business confidence and the broader South African economy.
South Africa’s producer price inflation eased to 5.0% year-on-year in August 2026, but persistent fuel and energy shocks continue to place pressure on the economy and keep inflation well above the South African Reserve Bank’s new 2%–4% target range. Although the pace of price increases has slowed, rising costs in petroleum, chemicals, metals, machinery, and intermediate goods, alongside elevated mining costs, suggest that inflationary pressures are still filtering through to businesses and consumers. With consumer inflation at 4.4% and the Reserve Bank having raised interest rates by 25 basis points, this report examines what the latest PPI trends mean for South Africa’s inflation outlook, interest-rate decisions, and the cost pressures likely to shape the economy in the months ahead.
When the South African Reserve Bank unexpectedly tightened monetary policy by 25 basis points to 7.25%, pushing the prime lending rate to 10.75%, it aimed to anchor inflation against imported oil shocks, but at what cost to an already bleeding real economy? With South Africa’s GDP contracting by 0.2%, unemployment climbing to 33.6%, and mining and manufacturing output in reverse, our economic challenge is not an overheated consumer base, but a severe supply-side squeeze. Raising the cost of capital cannot lower global crude prices; instead, it delivers a direct hit to strained household balance sheets and further stifles already anaemic Gross Fixed Capital Formation (GFCF). Dive into the full analysis to unpack why orthodox monetary tools miss the mark in an economy rationing out of necessity, what Governor Lesetja Kganyago’s latest guidance reveals about the interest rate path ahead, and how corporate leaders and investors must position their capital to navigate South Africa’s “higher-for-longer” reality.
South Africa’s August 2026 inflation data present a complex outlook: headline CPI rose to 4.4%, remaining below market expectations yet above the upper limit of the inflation target range, while services inflation continued to climb, and fuel and transport costs exerted further pressure on households and businesses. With the economy contracting, international oil prices rising and global uncertainties, including Middle East tensions and tariff disputes, continuing to weigh on the rand and domestic prices, attention is now focused on the South African Reserve Bank’s next interest-rate decision. Read the full report for an analysis of the factors driving inflation, the risks facing the economy and what the latest developments could mean for consumers, businesses and monetary policy in the months ahead.