Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
May 29, 2025

Producer Price Inflation

April 2025
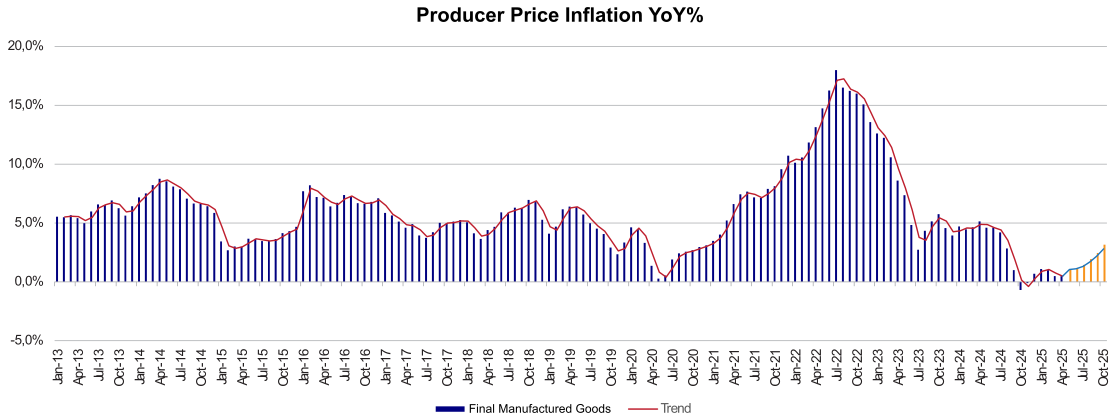
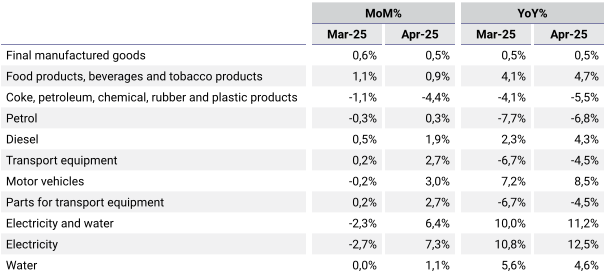
In April 2025, producer price inflation experienced another modest annual increase of 0.5%, unchanged from March 2025. Notably, food and beverage production costs grew by 4.7%, contributing 1.4 percentage points to this increase.

Although deflation persists in several categories, significant annual declines were recorded in products like coke, petroleum, chemicals, rubber, and plastics, which fell by 5.5% from a 4.1% drop in March. Transport equipment also decreased by another 4.5%, petrol by 6.8%, and parts for transport equipment by 4.5%. Production costs for intermediate goods rose by 8.5% in April following the 7.4% in March, surpassing the South African Reserve Bank’s (SARB) inflation target of 3% to 6% yet again. The month-on-month rise was a mere 2.4%, with inflationary pressure largely attributed to base effects from 2024 data. Key contributors to the annual increase included:

  • Gold and metal ores: rising 21.7% and adding 5.8 percentage points.
  • Non-ferrous metal ores: up 2.9%, contributing 1.5 percentage points.
  • Stone quarrying, clay, and diamonds: up 26.0%, contributing 1.1 percentage points.

Mining costs in the primary sector increased by 4.1% in April following the 5.9% the prior month, while the agriculture sector saw a 4.4% rise, following March’s 2.4% increase. Overall, the producer price inflation for final manufactured goods trend still support favourable inflation expectations in South Africa, with consumer inflation at 2.8%, below 3.0%. Despite the rise in intermediate goods prices, particularly water and electricity, being above SARB’s target, current producer inflation figures suggest consumer inflation will remain low and stable in the near term. This stability might just prompt the Reserve Bank to lower the interest rate today (29th of May 2025) as inflation expectation from both the consumer and producer side of the economy seems to be contained for the time being.


More Coverage

South Africa is trapped in severe economic stagnation, facing a projected 1.0% growth rate for 2026, 33.6% unemployment, and sharp contractions in mining (-12.7%) and manufacturing (-4.3%). Exposed to global fuel shocks via depleted reserves and >R12.00/litre pump levies, the nation is also caught in a fiscal spiral where national debt nears 80% of GDP and interest payments exceed R1 billion daily. Escaping this trap requires four urgent structural reforms: halting interest rate hikes for supply-side inflation, replacing rigid B-BBEE quotas with job-creation incentives, scrapping Expropriation Without Compensation (EWC), and deregulating Transnet’s logistics corridors.
South Africa’s mining sector remains a vital source of jobs, foreign exchange and economic growth, but August’s sharp fall in mining output and sales highlights the mounting pressure on the industry. Rising fuel and energy costs, policy uncertainty and growing trade challenges are weighing on producers, even as firm gold prices and temporary US tariff exemptions offer some relief. Read the full report for a closer look at the latest figures, the forces shaping the sector and what they could mean for mining’s future in South Africa.
A $100-plus oil price, a weaker rand and record fuel hikes are putting South Africa’s economy under mounting pressure, while strategic reserves offer little protection. This report examines how imported inflation is squeezing households and businesses, why higher interest rates may do little to tackle its root causes, and how sluggish growth and rising debt are tightening the fiscal squeeze. It also explores the stakes for trade with the United States and AGOA, and the policy choices that could restore investor confidence, unlock growth and put the country on a more resilient path.
South Africa recorded a trade surplus of R20.4 billion in August 2026, as exports continued to outpace imports. Export growth has exceeded import growth over the first eight months of the year, reflecting subdued domestic demand among businesses and consumers. But with higher fuel prices and tighter monetary policy expected to weigh on spending, demand is likely to recover only gradually. Read the full report for a closer look at the trade figures and what they could mean for South Africa’s economy in the months ahead.
South Africa’s credit market is showing surprising resilience, with credit demand rising by 7.5% in August 2026 despite renewed interest-rate pressure, elevated inflation and mounting household costs. While mortgage advances continued to grow, the fragile recovery in the property market highlights the strain caused by subdued investment, high debt levels and rising municipal and energy expenses. At the same time, sluggish instalment credit growth and continued reliance on short-term borrowing reveal how consumers are navigating increasingly difficult financial conditions. With higher oil prices, geopolitical risks and further SARB tightening adding to the pressure, this report examines what the latest credit trends reveal about household finances, business confidence and the broader South African economy.