

MACROECONOMIC & POLICY BRIEFING
The SARB’s Blunt Instrument: Why a 25 bps Rate Hike Misses the Mark for South Africa’s Strained Economy
An analysis of the Monetary Policy Committee’s latest rate hike, the risks of imported inflation, and the real-economy repercussions for households and productive investment.| ANALYSIS: South African Monetary Policy & Economic Outlook
In a move that divided financial analysts and will send a sharp chill through both domestic boardrooms and household living rooms, the South African Reserve Bank’s (SARB) Monetary Policy Committee (MPC) resolved to hike the benchmark repo rate by 25 basis points.
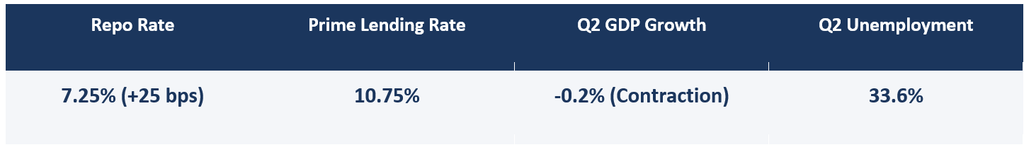
This decision lifts the repo rate to 7.25%, pushing the commercial banks’ prime lending rate to 10.75%—levels last witnessed in June 2025. Reserve Bank Governor Lesetja Kganyago confirmed that the six-member committee voted unanimously to tighten policy, defending the move as an essential measure to anchor medium-term inflation expectations amid intensifying international energy shocks.
While orthodox central banking doctrine dictates that monetary authorities must defend their price-stability mandate at all costs, this tightening arrives at a precarious juncture for the domestic real economy. South Africa is neither running a hot engine nor grappling with excessive consumer demand. By pushing rates higher into an already-contracting economy, the SARB risks deepening domestic structural scars without meaningfully alleviating the imported price pressures that are driving headline inflation.
The SARB’s Stance: Chasing Second-Round Phantoms
Delivering the MPC’s statement, Governor Kganyago articulated the central bank’s growing unease with external supply shocks. While acknowledging that domestic food inflation has decelerated to its lowest level since 2010 and the rand has demonstrated commendable resilience, the central bank highlighted that the international fuel-price shock has re-accelerated rather than dissipated.
| “A few months back, it seemed that the fuel-price shock might be unwinding, but now it has intensified… Shocks are multiplying, and vulnerabilities are increasing. The global economy is not in a healthy space. It is crucial that inflation reverts to 3% as the current shock fades, and we take responsibility for delivering that outcome.” — Lesetja Kganyago, SARB Governor |
With petrol showing an average under-recovery of R2.83 per litre and consumer price index (CPI) headline inflation climbing slightly to 4.4% in August (up from 4.3% in July), the central bank updated its projections, warning that headline inflation will likely breach 5% later this year before moderating back towards the 3% target by late 2027. To prevent these large, sustained input cost spikes from embedding themselves into generalised wage demands and retail price setting, the classic ‘second-round effects’, the MPC determined that a more restrictive policy stance was strictly required.
The Reality Check: Contraction, Not Overheating
From an economic and investment standpoint, the fundamental conflict lies between the assumptions of monetary models and the empirical realities of South Africa’s macroeconomic landscape. Monetary tightening is designed to cool an overheating economic engine, one where exuberant consumer spending, tight labour markets, and cheap credit fuel a price spiral. South Africa faces precisely the inverse condition:
- A Contracting Real Economy: Gross Domestic Product (GDP) contracted by 0.2% in the second quarter of 2026, dragged down by acute output declines across critical productive pillars, most notably mining and manufacturing.
- Deepening Unemployment Scars: Official unemployment worsened to 33.6% in Q2 2026, underlining an acute inability of the domestic economy to absorb labour or generate aggregate disposable income.
- Depressed Domestic Demand: Underlying core inflation prints confirm that demand-pull pressure across discretionary consumer goods is virtually non-existent. South African consumers are not spending out of abundance; they are rationing out of necessity.
Higher interest rates cannot influence the international Brent crude price benchmark, untangle global supply bottlenecks, or resolve domestic logistical constraints. When cost inflation originates externally through dollar-denominated fuel imports, raising borrowing costs serves as a blunt and inefficient instrument. It seeks to suppress price indices by artificially constraining the only variable within monetary reach: domestic aggregate demand and borrowing appetite.
Household Budgets & Fixed Investment: The Real Casualties
The collateral damage of this 25 bps hike will land squarely upon two fragile pillars that are indispensable for long-term recovery:
1. Overstretched Household Budgets
South African households are already besieged by compounding cost pressures, including above-inflation municipal tariff hikes, escalating electricity costs, and rising food transport margins. With the prime lending rate elevated to 10.75%, debt servicing obligations on home bonds, vehicle asset finance, and revolving facilities will jump immediately. Every additional rand allocated to mortgage interest service is a rand stripped directly from retail turnover, services, and domestic savings.
2. Fixed Capital Formation (GFCF) Stagnation
The more profound structural concern resides on the capital investment frontier. South Africa’s Gross Fixed Capital Formation (GFCF) as a percentage of GDP remains at a critically depressed level, hovering around 14%-15%, far below the National Development Plan’s target of 30%.
Long-term physical capital formation, factory upgrades, mining shaft recapitalisation, renewable energy development, and commercial logistics expansion require a manageable cost of capital and investment certainty. Jacking up real financing rates into a contracting production environment raises the hurdle rate for capital projects, deterring domestic firms from committing balance-sheet capital. In attempting to protect the currency’s purchasing power tomorrow, policy risks choking the productive capacity needed to build wealth today.
Strategic Outlook: Navigating ‘Higher-for-Longer’
If there is any comfort for corporate treasuries and debt issuers, it is that this hike appears to represent the cyclical ceiling. According to the SARB’s Quarterly Projection Model (QPM), the policy rate is projected to remain broadly stable for the remainder of 2026, with prospective rate cuts pushed further out into the later forecast periods once inflation reliably retraces toward 3%.
Ultimately, sustainable economic revival and enduring price stability will not be engineered within the walls of the Reserve Bank’s MPC boardroom alone. Genuine disinflation is achieved through a robust, competitive supply-side economy, characterised by structural network reforms, reliable freight logistics, uninterrupted power, and aggressive physical capital investment. Until South Africa’s structural impediments are decisively dismantled, relying on monetary contraction to counter global supply shocks imposes an unreasonable burden on an already strained domestic economy.


