Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
July 22, 2026

The SARB’s Dilemma: Why a 25-Basis-Point Rate Hike Would Be the Wrong Medicine for South Africa

In “The SARB’s Dilemma: Why a 25-Basis-Point Rate Hike Would Be the Wrong Medicine for South Africa,” the article highlights the crucial choice facing the South African Reserve Bank (SARB) amid rising inflation, driven primarily by external factors like global oil volatility. As the Monetary Policy Committee prepares to meet, the piece argues against the anticipated 25-basis-point increase in the repo rate, asserting that such action would unfairly burden households and businesses already grappling with financial strain. Instead, the article advocates for a hold position, emphasizing that this approach would preserve liquidity in a struggling economy, support private sector growth, and allow for necessary structural reforms to take root. Readers will find compelling insights on the economic implications of SARB’s decision and the importance of distinguishing between domestic demand and external pressures.

With Statistics South Africa confirming that June consumer price inflation (CPI) accelerated to 5.0%, up from 4.5% in May, all eyes turn to the South African Reserve Bank’s (SARB) Monetary Policy Committee (MPC) announcement tomorrow. The latest inflation spike is driven almost entirely by a 12.7% annual surge in transport costs, reflecting global crude oil volatility and geopolitical friction in the Middle East.

Against this backdrop, market consensus and central bank orthodoxy suggest that the SARB will likely announce a 25-basis-point increase in the repo rate tomorrow, taking it to 7.25% and pushing the prime lending rate to 11.75%. However, while a rate hike may be the most probable outcome, it is not the correct one. The MPC would be far better advised to opt for an interest rate hold position.

Taming Supply-Side Inflation with a Demand-Side Hammer

The central problem facing South Africa’s monetary authorities is that our current inflationary pressures emanate entirely from outside our domestic economic system. High international oil prices and global shipping disruptions are supply-side shocks, factors over which the Reserve Bank has zero direct control.

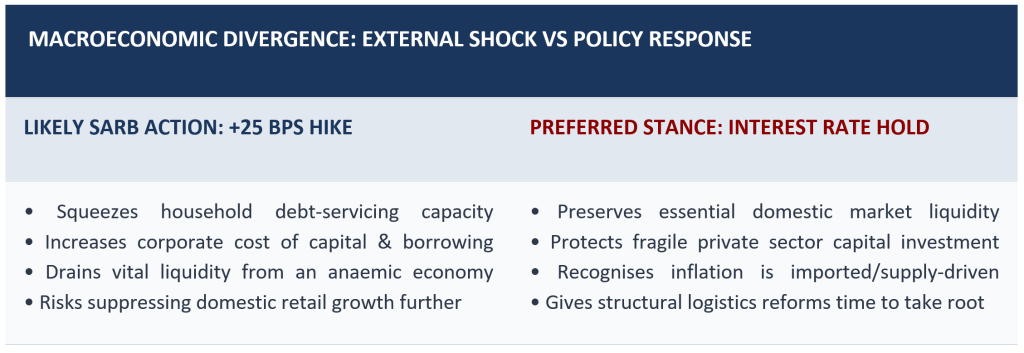
Raising domestic borrowing costs will not lower Brent crude prices, nor will it calm international trade route tensions. What it will do, however, is directly penalise South African households and businesses that are already struggling under immense financial strain. When you use higher interest rates to combat imported, cost-push inflation, you are essentially trying to cure an external supply constraint by crushing domestic consumer demand.
Draining Liquidity from an Anaemic Economy

South Africa’s macroeconomy remains inherently anaemic, desperately needing sustained economic growth, private sector capital formation, and job creation. By hiking rates further, the central bank risks draining vital liquidity from the financial system at a time when local businesses require affordable working capital to expand operations and hire workers.

  • Impact on Consumers: Higher debt-servicing burdens on mortgages, vehicle finance, and credit cards directly reduce disposable income, further dampening retail demand and consumer confidence.
  • Impact on Businesses: Elevated borrowing costs disincentivise capital expenditure (CapEx), forcing small-to-medium enterprises (SMEs) to scale back expansion plans, delay equipment upgrades, or freeze hiring.
  • Impact on Macro Growth: Suppressing domestic activity when underlying economic momentum is already muted creates structural drag, making our longer-term target of 2.0%+ GDP growth far harder to achieve.

Why a Hold Position Makes Economic Sense

A hold position would send a strong, reassuring signal that monetary policy understands the clear distinction between domestic demand overheating and external cost pushes. While the SARB naturally worries about ‘second-round effects’, where fuel price increases spill over into broader wage and price expectations, domestic demand is simply too weak to sustain broad-based wage-price spirals. Stripping out transport and fuel, core inflation dynamics remain relatively contained.

Furthermore, long-term structural reforms currently underway in domestic electricity, freight rail, and port logistics, supported by major capital investments and Special Economic Zones, are the true, sustainable mechanisms for lowering the cost of doing business in South Africa over time.
The Verdict

Tomorrow afternoon, the Governor will likely announce a cautious 25-basis-point rate hike to defend the inflation target and insulate the Rand against foreign capital outflows. Predicting a hike is a realistic assessment of central bank risk-aversion. However, South Africa needs space to breathe, invest, and build, and that requires a stable borrowing environment rather than further monetary tightening.


More Coverage

South Africa’s retail sector delivered a striking surprise in July 2026, with sales climbing 3.4% against market expectations of a 3.0% contraction, but the story beneath that headline number is far more nuanced than it first appears. This report unpacks the fragile balancing act facing local households: inflation easing to 4.3% yet still stubbornly above the SARB’s new 2–4% target band, administered prices and utility costs rising by more than 4.0%, wage growth lagging behind severe fuel shocks, and the lingering effect of May’s 25-basis-point rate hike prompted by inflationary pressures well beyond Pretoria’s control. We examine why business confidence firmed (SACCI up from 123.5 to 125.4) while consumer sentiment slumped sharply (FNB/BER down from -7 to -19), which categories, from “other retailers” to general dealers and household goods, actually carried the growth, and what the extension of AGOA to end-2027 means now that fresh visa tensions between Washington and Pretoria have placed South Africa’s eligibility squarely under the microscope. Read the full report to understand whether this recovery has the legs to survive higher fuel prices, a possible second rate increase, and a second-quarter contraction in economic activity — or whether July’s good news was simply borrowed from the easing cycle of 2024/25.
South Africa’s business profitability showed surprising resilience in the second quarter of 2026, outpacing inflation despite a 0.2% contraction in economic activity, higher oil and import prices, trade tariffs, and ongoing diplomatic tensions. While overall profit growth slowed from the first quarter, several sectors, including transport and logistics, mining, electricity and utilities, personal services, and trade, recorded substantial gains, offering important clues about where the economy’s strongest opportunities may lie. This report examines the forces shaping Gross Operating Surplus across key industries, explains the mounting pressures on company performance, and considers whether easing geopolitical tensions, lower oil prices, and greater policy certainty could unlock stronger economic activity, employment, and investment in the months and years ahead.
South Africa’s international liquidity position strengthened in August 2026, with net gold and foreign exchange reserves rising by USD 1,9 billion as the rand gained nearly 30c against the US dollar and the gold price climbed to USD 4 460/oz, some 30% higher than a year earlier. Yet beneath these encouraging headline figures lies a far more complex picture: the ongoing conflict in the Middle East and tensions around the Strait of Hormuz are keeping oil prices elevated, while shifting US tariff measures, a one-year AGOA extension and the Federal Reserve’s decision to hold rates steady all point to continued volatility for the rand. With the South African Reserve Bank’s third-quarter interest rate decisions hanging in the balance, this report unpacks what these commodity and currency movements mean for inflation, the mining sector and South Africa’s economic outlook for the remainder of the year.
South Africa’s mining sector is facing mounting pressure, with production falling 7.5% in July 2026 after a revised 4.3% decline in June, while the rolling three-month contraction reached 5.5% and nominal mining sales dropped 5.6%. Sharp declines in iron ore, coal, PGMs, gold, manganese, and nickel highlight the sector’s vulnerability, compounded by job losses, rising fuel and energy costs, policy uncertainty, property rights concerns, and growing trade barriers. Yet mining remains indispensable to the economy, supporting approximately 450,000 jobs, generating foreign exchange and contributing to growth. With elevated gold prices and temporary tariff exemptions offering limited relief, this report examines the forces reshaping South Africa’s mining industry—and whether these bright spots can withstand the sector’s deepening structural and geopolitical challenges.
South Africa’s economy faced renewed pressure in the second quarter of 2026, contracting by 0.2% amid high input costs, elevated fuel prices and challenging global conditions. While sectors such as agriculture and finance showed resilience, continued weakness in manufacturing, mining and trade highlights the structural challenges facing the economy. With unemployment remaining elevated and inflationary pressures still a concern, policy clarity, infrastructure investment and improved business confidence will be critical to supporting sustainable economic growth in the months ahead.