Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
August 27, 2026

Producer Price Inflation – July 2026
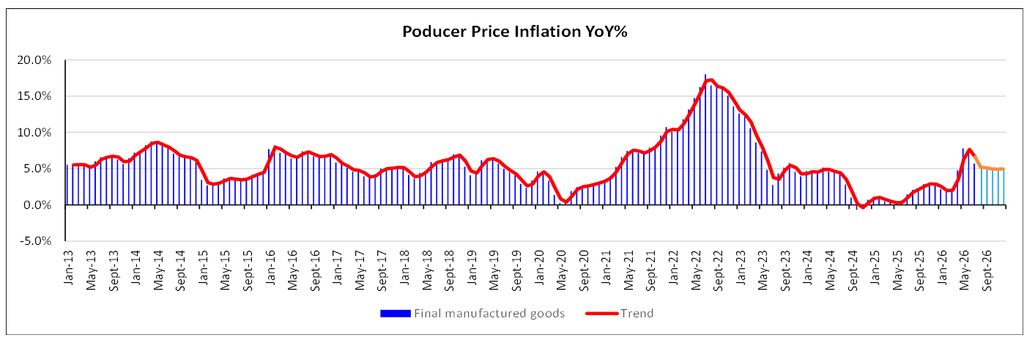
South Africa’s producer price inflation eased from 7.5% to 5.7% year-on-year in July 2026, but the slowdown offers little comfort as rising fuel, energy and intermediate-goods costs continue to reverberate through the economy. With petroleum-related products driving much of the increase, mining costs still elevated, and consumer inflation already above the South African Reserve Bank’s new target range, inflationary pressures remain firmly entrenched, even as monthly producer prices declined. This report examines the sectors driving the latest figures, the implications of ongoing Middle East-related energy shocks, and what the data could mean for consumer prices, inflation expectations, and the Reserve Bank’s upcoming interest-rate decision in September.

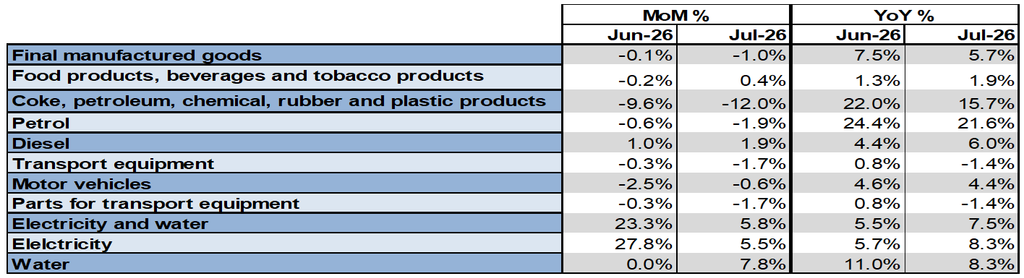
In July 2026, producer price inflation increased by 5.7% year-on-year, down from 7.5% in June, as fuel price shocks trickled through the economy into the prices of goods leaving the factory gate. However, producer inflation decreased by 1.0% monthly during July, while the annual increase was mostly due to  cost increases in the following categories:

  • Coke, petroleum, chemical, rubber and plastic products: Increased by 15.7% and contributed 3.4 percentage points,
  • Food and Beverage Production: Increased by 1.9% and contributed 0.6 percentage points,
  • Metals, machinery, equipment and computing equipment: Rose by 3.8% year-on-year while contributing 0.6 of a percentage point.

Production costs for intermediate goods rose by another 9.8% following the 12.4% in June 2026. This indicates that a clear inflationary trend is still ongoing, even though the pace of escalation is slowing a bit. These increases still greatly exceed the South African Reserve Bank’s (SARB) new inflation target range of 2% to 4%. Annual growth is still significantly influenced by increases in fuel and energy prices resulting from the conflict in the Middle East and the subsequent closure of the Strait of Hormuz.

In the primary sector, mining costs climbed by 9.6% in July, following a 18.4% rise in June. In contrast, the agriculture sector experienced a further 4.5% decline, following a 7.9% decrease the previous month.

Overall, the trend in producer price inflation remains above the SARB’s upper target, albeit at a slower rate of escalation in producer prices for final manufactured goods, and this does not bode well for general consumer inflation and inflation expectations in South Africa in the short to medium term. Consumer inflation still exceeds the upper band of the new target range, at 4.3% in July. While prices for certain intermediate goods—particularly water and electricity—continue to exceed the target range, current figures suggest consumer inflation will likely remain elevated in the short- to medium-term, as energy price shocks continue to reverberate throughout the economy.

The Reserve Bank’s upcoming interest rate decision will consider both the Consumer Price Index (CPI) and the Producer Price Index (PPI) when analysing inflation expectations, as price stability remains the key concern for the Bank in making interest rate decisions for South Africa.


More Coverage

South Africa’s latest inflation figures provide some welcome relief, but a renewed surge in global oil prices threatens to undermine this progress. With fuel prices rising sharply due to external geopolitical and supply-side pressures, the debate over whether the SARB should respond with higher interest rates has become increasingly important. This article argues that raising rates to combat imported inflation would risk doing more harm than good—placing further pressure on households, businesses and investment in an economy already facing weak growth, high unemployment and significant industrial challenges.
Private sector credit growth remained resilient in July 2026, reflecting continued demand for financing despite elevated living costs and renewed interest rate uncertainty. While overall credit extension continues to benefit from the rate-cutting cycle that began in late 2024, subdued property activity and rising household reliance on short-term credit highlight ongoing pressure on consumers and businesses.
South Africa’s producer price inflation eased from 7.5% to 5.7% year-on-year in July 2026, but the slowdown offers little comfort as rising fuel, energy and intermediate-goods costs continue to reverberate through the economy. With petroleum-related products driving much of the increase, mining costs still elevated, and consumer inflation already above the South African Reserve Bank’s new target range, inflationary pressures remain firmly entrenched, even as monthly producer prices declined. This report examines the sectors driving the latest figures, the implications of ongoing Middle East-related energy shocks, and what the data could mean for consumer prices, inflation expectations, and the Reserve Bank’s upcoming interest-rate decision in September.
South Africa has received a much-needed inflation reprieve, with July headline inflation easing to 4.3% and giving the South African Reserve Bank room to hold interest rates steady, but monetary relief alone cannot rescue an economy facing contracting mining and manufacturing sectors, depressed investment, mass unemployment, and mounting pressure on export earnings. This report examines how a 12.5% US tariff and a 56% annualised plunge in exports are intensifying the country’s economic vulnerability, while diplomatic disputes over property rights, empowerment policy, rural safety, political rhetoric, and South Africa’s geopolitical alliances threaten access to the strategically vital US market. It also sets out the practical policy choices, from structural reform and infrastructure investment to pragmatic trade diplomacy, that could determine whether South Africa converts this brief moment of inflation stability into sustainable growth or slips deeper into stagnation
South Africa’s July 2026 inflation reading delivered a genuine surprise: consumer prices rose just 4.3% year-on-year, well below June’s 5.0% and under the 4.5% the market had pencilled in, yet the story beneath that headline is far more complicated than a simple cooling trend. Goods inflation has slipped into the SARB’s new 2–4% target band, but services inflation stubbornly holds at 5.0%, revealing that price pressure is now entering the economy through a channel monetary policy struggles to reach. Meanwhile, housing, transport, and financial services drove the bulk of the increase; fuel costs remain elevated amid the renewed Middle East conflict and rising oil prices; and households and businesses relying on short-term credit are dangerously exposed to any shift in rates, the rand, or import costs. Add US tariffs weighing on manufacturing, fragile 0.5% first-quarter growth, and a Reserve Bank that has already wrong-footed markets twice this year, and the run-up to the 23 September MPC meeting becomes anything but predictable. This report unpacks what the numbers actually signal, why the SARB is holding its nerve, and what it will take to tip the next rate decision either way.