

MACROECONOMIC & INVESTMENT INSIGHTS | OCTOBER 2026
Between the Oil Shock and the Fiscal Squeeze
Why Imported Inflation, Soaring Fuel Prices, and Policy Inertia Threaten South Africa’s Economic Trajectory
1. The Brewing Geopolitical and Energy Storm
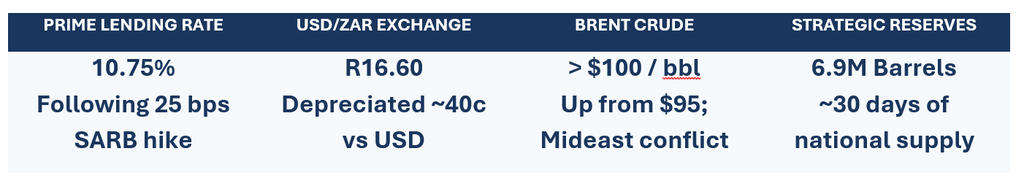
The South African economy is confronting a fierce convergence of international headwinds. Escalating hostilities in the Middle East have reignited volatility across maritime transit routes, with tensions around the Strait of Hormuz and the Houthi blockade on crude shipping through the Bab al-Mandeb Strait choking supply corridors. In response, international crude has spiked from $95 per barrel to surpass the psychological $100 mark.
Compounding this international oil shock, the South African Rand has come under intense pressure. Having slipped from R16.20 to lows of R16.74 before settling around R16.60 against the US Dollar, the local currency has ceded roughly 40 cents in value. For South Africa, an economy that imports most of its crude and refined fuel requirements, the double blow of a depreciating domestic currency and rising dollar-denominated crude oil prices is a toxic dynamic.
The practical fallout was confirmed yesterday when the Central Energy Fund (CEF) officially gazetted record fuel price hikes for October. Diesel price increases, in particular, will serve as a transmission line for broader domestic cost pressures. Because our transport, agricultural, and retail supply chains depend fundamentally on heavy road logistics, surging diesel prices do not stay at the filling station; they work their way straight into shelf prices and everyday services.
| Strategic Vulnerability: The Cushion That Vanished Our vulnerability to international energy shocks is profoundly magnified by the state of national strategic reserves. Managed by the Strategic Fuel Fund (SFF), South Africa’s strategic crude reserves currently stand at a perilous 6.9 million barrels—providing barely 30 days of national consumption cover. This is a dramatic drop from the historical peak of 158.5 million barrels in the mid-1970s, leaving much of the country’s 58-million-barrel storage capacity empty. The controversial, unhedged sell-off of strategic stock years ago remains under endless investigation with no accountability. As a result, the economy faces turbulence in the global oil market without a safety net. |
2. The SARB’s Dilemma: Using a Blunt Tool on Imported Costs
The October fuel shock arrives directly on the heels of the South African Reserve Bank’s (SARB) September decision to lift the repo rate by another 25 basis points, pushing the prime lending rate to 10.75%. The Monetary Policy Committee defended this tightening as necessary to anchor inflation expectations, with headline CPI breaching the upper limit of the Bank’s target band.
Yet, from a macroeconomic perspective, the nature of South Africa’s inflationary pressure must be scrutinised. This is not a classic demand-pull inflation where ‘too many Rands are chasing too few goods.’ Consumer demand is not running hot; it is severely depressed. Domestic price pressures stem almost entirely from cost-push factors, higher international crude oil prices, administered prices, and import pass-through, forces completely outside the realm of domestic interest rate policy.
Raising borrowing costs does nothing to lower Brent crude prices in London or stabilise tanker traffic in the Red Sea. What it does achieve, however, is the penalisation of domestic households and businesses that are already stretched thin. Commercial retail banks are already flagging across-the-board rises in credit impairments and bad debts across unsecured credit, vehicle financing, and residential mortgages. Crushed by high debt-servicing costs, household disposable income is declining, squeezing discretionary spending and depressing margins in retail and cyclical businesses.
3. The Fiscal Trap: Bond Yields, Rising Debt, and Weak Growth
The economic slowdown has directly compromised the fiscus. Following a 0.2% contraction in GDP in the second quarter of 2026 and official unemployment remaining stubbornly at 33.6%, millions more citizens are reliant on state social grants and basic relief. This widening of the social safety net increases the government’s borrowing requirement at the worst possible time.
In standard economic textbook models, bond yields and interest rates typically move inversely. In South Africa, however, government bond yields have defied the textbook, climbing 50 basis points year-to-date. The 10-year sovereign bond yield (SAGB) trades stubbornly high between 8.78% and 8.82%. This elevated yield reflects a hefty fiscal risk premium demanded by investors as South Africa’s gross consolidated debt races past R10.68 trillion.
To be sure, global and domestic fixed-income capital still covets these elevated returns. In a recent National Treasury auction, primary dealers placed orders totalling R16.3 billion against R2.55 billion on offer, a more than sixfold oversubscription. However, this bond market appetite is a double-edged sword: high yields signify high borrowing costs for the State. Ahead of the Medium-Term Budget Policy Statement (MTBPS), debt-service costs are consuming an ever-larger share of the national revenue envelope, leaving virtually no room for growth-enhancing capital expenditure or the maintenance of physical infrastructure.
4. Repairing Geopolitical Bridges: The AGOA Priority
To break this potential stagflationary cycle, South Africa must urgently secure foreign exchange earnings and expand outbound trade. No economic objective is more pressing than salvaging and revitalising our trade relationship with the United States. South Africa’s bilateral trade with the US has tumbled by nearly 60% amid punitive tariffs and frostier diplomatic relations. Crucial high-value sectors, such as commercial agriculture in the Western Cape, automotive manufacturing in the Eastern Cape, and advanced metals, are paying the price for political posturing on the world stage.
With preferential access under the African Growth and Opportunity Act (AGOA) facing continuous scrutiny, preserving our place in the arrangement must be treated as a critical matter of national economic interest. South Africa cannot afford to alienate its largest and most lucrative export markets at a time when foreign direct investment and export-driven foreign exchange are vital to stabilising the balance of payments.
5. Unlocking Growth: The Structural Policy Imperative
The ultimate pathway out of stagnation will not come from fine-tuning repo rates, nor can National Treasury indefinitely borrow its way out of trouble. Sustainable relief requires bold, market-friendly reforms that restore “capital-confidence” and revive Gross Fixed Capital Formation (GFCF).
- Monetary Pragmatism: The SARB must recognise that tightening policy cannot resolve imported energy costs or administered tariffs. Further rate hikes will merely suffocate the fragile productive sectors.
- Modernising Economic Empowerment: The time has come to overhaul bureaucratic, outdated Broad-Based Black Economic Empowerment (B-BBEE) frameworks and roll back the restrictive provisions of the Employment Equity Amendment Act 4 of 2022. Replacing punitive compliance hurdles with incentives that promote job creation, technical training, and grassroots enterprise development will encourage domestic hiring and expansion.
- Guaranteed Property Rights: Government must permanently shelve Expropriation Without Compensation (EWC). Clear, unshakeable legal protection for private property is the non-negotiable bedrock required to unlock domestic and international fixed investment.
- Aggressive Deregulation: Eliminating bureaucratic red tape, fast-tracking port and rail concessioning, and lowering the cost of doing business will allow our industrial base to expand without state handouts.
Conclusion: The Political Will to Rebound
South Africa possesses immense mineral wealth, a world-class financial sector, and an entrepreneurial population eager for opportunity. Yet, as external oil shocks buffet our economy, our domestic policy bottlenecks exacerbate every shock. A few decisive, market-friendly policy adjustments can unleash billions in latent capital, revive employment, and provide the fiscal breathing room necessary to escape the debt spiral. What is needed now is not another round of restrictive austerity or dogmatic rate hikes, but the political resolve to build a pro-investment economy.


