Copyright © Aluma Capital (Pty) Ltd. All rights reserved.
Aluma Capital (Pty) Ltd is a registered Financial Services Provider (FSP 46449) in terms of The Financial Advisory and Intermediary Services Act (37 of 2002)
August 13, 2026

South African Gold and Foreign Exchange Reserves for July 2026
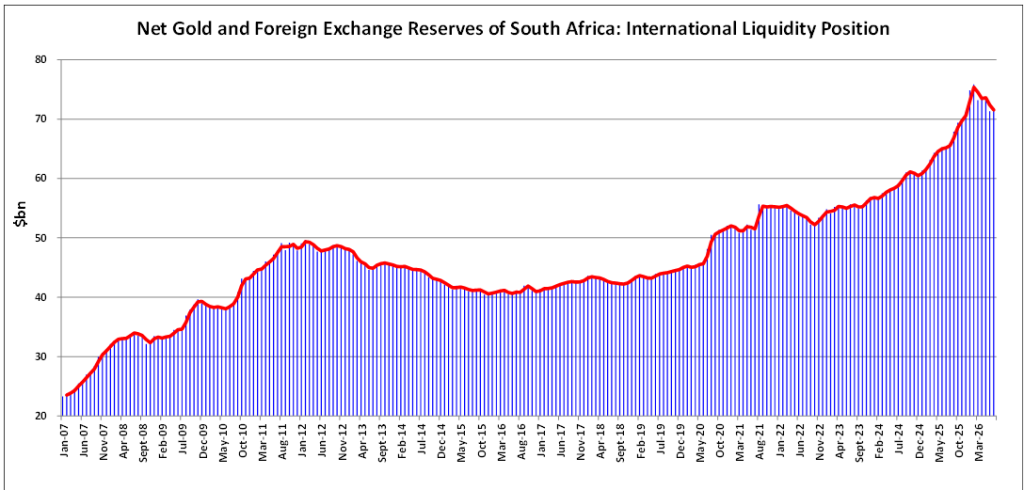
South Africa’s international liquidity position reveals a complex economic landscape shaped by global geopolitical tensions, commodity price dynamics, and evolving trade relationships. While Net Gold and Foreign Exchange Reserves showed modest growth in July 2026, buoyed by historically elevated gold prices and strategic central bank interventions, underlying pressures, including Middle East conflict-driven fuel costs, currency volatility, and shifting US trade policies, threaten inflation stability and monetary policy decisions in the months ahead. This comprehensive analysis examines how commodity trends, Reserve Bank operations, and international developments are converging to shape South Africa’s economic trajectory, offering critical insights into what investors, policymakers, and businesses should monitor as the country navigates tariff uncertainties, geopolitical risks, and the critical third-quarter interest rate decisions that could define economic performance for the remainder of 2026.

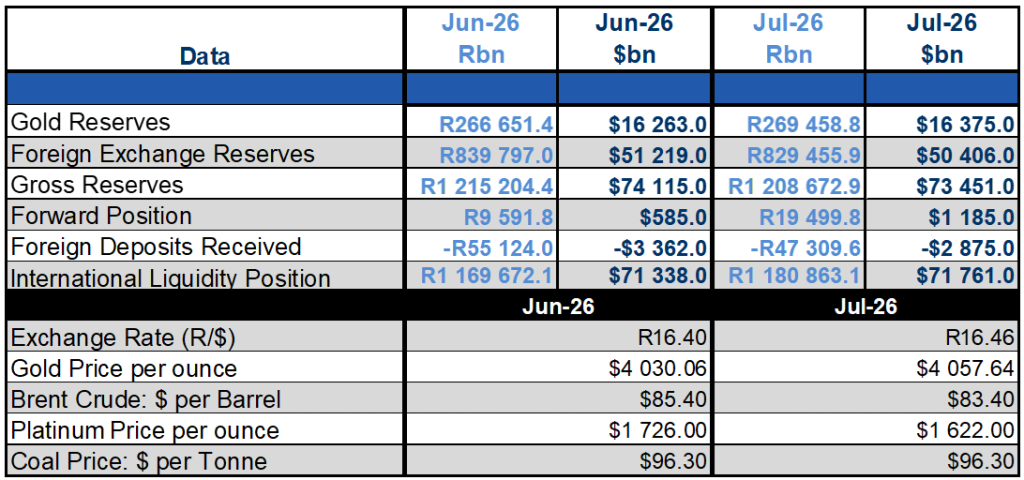
The South African International Liquidity Position, measured by Net Gold and Foreign Exchange Reserves, showed a marginal increase in both USD terms and in Rand terms for July 2026. The Rand depreciated slightly against the US Dollar from June to July 2026 following the ongoing conflict in the Middle East, according to official reports from the South African Reserve Bank. Reserves increased by nearly USD 423 million, following a USD 2.1 billion decline recorded in June 2026. The gold price remains high, having increased slightly in July from $4030/oz recorded in June to $4057/oz, and is still 23% higher than the prior year’s price. The sustained high gold price played a significant role in supporting reserves from January through July amid the ongoing conflict in the Middle East.

In USD terms, foreign reserves decreased in July 2026 compared to the previous month. The Reserve Bank continued to sell off some US Dollars in open market operations, partly due to higher prices for imported fuel resulting from the ongoing conflict in the Middle East, thereby impacting South Africa’s net international liquidity position at that time.

Key commodities such as gold, oil, platinum, and coal offer valuable insights into South Africa’s mining sector and inflation outlook. Monitoring these trends is vital for assessing inflation prospects, especially amid ongoing international developments and potential trade restrictions with the US following August’s tariff measures.

Tracking these movements is crucial, as inflation expectations will influence the South African Reserve Bank’s (SARB) interest rate decisions during the third quarter of 2026, especially considering the ongoing conflict in the Middle East and the tensions around the Strait of Hormuz. A stable Rand, albeit slightly stronger for now, and higher oil prices than at the beginning of 2026 are conducive to higher inflation. However, continued global geopolitical tensions and possible changes to trade agreements, such as the African Growth and Opportunity Act (AGOA), which has been extended by one year by the US administration, could introduce increased market volatility, as the 30% reciprocal tariffs were reduced to 12.5% for now as the US Supreme Court ruled that the 30% tariffs were unconstitutional and had to be removed. With recent US tariffs and the Federal Reserve’s decision to hold interest rates steady at its 29th of July 2026 announcement, the Rand may continue to experience short-term fluctuations, even as it appreciated against the US Dollar, which could affect South Africa’s economic outlook for the remainder of the year.


More Coverage

South Africa recorded a trade surplus of R20.4 billion in August 2026, as exports continued to outpace imports. Export growth has exceeded import growth over the first eight months of the year, reflecting subdued domestic demand among businesses and consumers. But with higher fuel prices and tighter monetary policy expected to weigh on spending, demand is likely to recover only gradually. Read the full report for a closer look at the trade figures and what they could mean for South Africa’s economy in the months ahead.
South Africa’s credit market is showing surprising resilience, with credit demand rising by 7.5% in August 2026 despite renewed interest-rate pressure, elevated inflation and mounting household costs. While mortgage advances continued to grow, the fragile recovery in the property market highlights the strain caused by subdued investment, high debt levels and rising municipal and energy expenses. At the same time, sluggish instalment credit growth and continued reliance on short-term borrowing reveal how consumers are navigating increasingly difficult financial conditions. With higher oil prices, geopolitical risks and further SARB tightening adding to the pressure, this report examines what the latest credit trends reveal about household finances, business confidence and the broader South African economy.
South Africa’s producer price inflation eased to 5.0% year-on-year in August 2026, but persistent fuel and energy shocks continue to place pressure on the economy and keep inflation well above the South African Reserve Bank’s new 2%–4% target range. Although the pace of price increases has slowed, rising costs in petroleum, chemicals, metals, machinery, and intermediate goods, alongside elevated mining costs, suggest that inflationary pressures are still filtering through to businesses and consumers. With consumer inflation at 4.4% and the Reserve Bank having raised interest rates by 25 basis points, this report examines what the latest PPI trends mean for South Africa’s inflation outlook, interest-rate decisions, and the cost pressures likely to shape the economy in the months ahead.
When the South African Reserve Bank unexpectedly tightened monetary policy by 25 basis points to 7.25%, pushing the prime lending rate to 10.75%, it aimed to anchor inflation against imported oil shocks, but at what cost to an already bleeding real economy? With South Africa’s GDP contracting by 0.2%, unemployment climbing to 33.6%, and mining and manufacturing output in reverse, our economic challenge is not an overheated consumer base, but a severe supply-side squeeze. Raising the cost of capital cannot lower global crude prices; instead, it delivers a direct hit to strained household balance sheets and further stifles already anaemic Gross Fixed Capital Formation (GFCF). Dive into the full analysis to unpack why orthodox monetary tools miss the mark in an economy rationing out of necessity, what Governor Lesetja Kganyago’s latest guidance reveals about the interest rate path ahead, and how corporate leaders and investors must position their capital to navigate South Africa’s “higher-for-longer” reality.
South Africa’s August 2026 inflation data present a complex outlook: headline CPI rose to 4.4%, remaining below market expectations yet above the upper limit of the inflation target range, while services inflation continued to climb, and fuel and transport costs exerted further pressure on households and businesses. With the economy contracting, international oil prices rising and global uncertainties, including Middle East tensions and tariff disputes, continuing to weigh on the rand and domestic prices, attention is now focused on the South African Reserve Bank’s next interest-rate decision. Read the full report for an analysis of the factors driving inflation, the risks facing the economy and what the latest developments could mean for consumers, businesses and monetary policy in the months ahead.